2026 11 10
Global Financial Briefing — Tuesday, 10 November 2026
Americas index levels, commodities and day changes reflect the 10 Nov 2026 close. The US Treasury par and real curves, the curve spreads and the US curve chart are at the 10 Nov 2026 close. The euro AAA curve is the 9 Nov 2026 observation, the latest the ECB had published. FX is the evening quote; credit and macro figures are dated inline.
Market Overview
US consumer prices rose faster than expected in October, and bond yields jumped on both sides of the Atlantic. The consumer price index rose 0.4% on the month against 0.3% forecast, and the core index, which leaves out food and energy, 0.3% against 0.2% (CNBC). No year-on-year rate was published, because October 2025 prices were not collected during last year's government shutdown. Hours before the release, Fed Governor Christopher Waller had said a half-point rise in December should be considered if core inflation came in around 0.3% (CNBC, ZeroHedge). After the figures, futures fully priced a quarter-point Fed rise at the 8 to 9 December meeting and put the odds of a half-point move at 13.6%, up from about zero before the report (CME FedWatch, via CNBC).
Short-dated Treasury yields rose most: the 2-year settled 17 bp higher at 4.73% and the 10-year 10 bp higher at 4.98%, while the 30-year rose 9 bp to 5.35% (US Treasury par curve, 10 November). The 10-year last closed above 5% on 28 October, at 5.05%. The S&P 500 closed down 0.38%, the Nasdaq 100 0.60% and the Dow 0.30%, giving back part of Monday's rally, when the S&P 500 rose 2.35% (CNBC). Most of the fall was in technology: the S&P 500's technology sector fund (XLK) fell 1.15%, while its financials (XLF) and energy (XLE) funds rose 0.52% and 0.44%. Nvidia fell about 5.5% (YourNews), after a 4.3% fall on Monday, amid reports of a US probe into alleged smuggling of its AI chips and of new export controls under consideration at the White House (ZeroHedge). The ICE dollar index rose 0.68% and the euro fell 0.55% to $1.1157 in the European evening; gold settled 2.05% lower.
Asia closed before the US figures and rallied on Monday's rebound in US chip shares: Korea's Kospi rose 4.39% and Japan's Nikkei 225 2.87% (CNBC). Europe was up about 0.9% in the morning, with lower oil and a 4.8% rise in Infineon after its results (CNBC), but gave back most of that by the close as yields rose after the US data; the STOXX 600 closed up 0.27% and the CAC 40 0.55%. The 10-year Bund yield reversed its early fall and rose 6 bp to 3.33%, and the 2-year gilt yield rose 13 bp (Trading Economics). Brent crude's January contract (BZF27) briefly traded below $90 for the first time since August, after President Trump said further strikes on Iran would not be needed and Qatar said US-Iran mediation had gained momentum (ZeroHedge); it settled at $91.49, down 1.17%.
Global Indices Snapshot
Americas
| Index | Level | Day Chg | Day Chg % | Source |
|---|---|---|---|---|
| S&P 500 | 7,520.93 | −29.01 | −0.38% | yfinance ^GSPC |
| Nasdaq 100 | 27,740.80 | −166.83 | −0.60% | yfinance ^NDX |
| Dow Jones | 52,231.89 | −157.91 | −0.30% | yfinance ^DJI |
| Brazil IBOV | 171,336.98 | −899.07 | −0.52% | yfinance ^BVSP |
Americas data reflects the 10 Nov 2026 close.
The S&P 500 is 2.02% below its 50-day average and 2.63% above its 200-day; the Nasdaq 100, down 0.60% on the day, is 6.29% below its 50-day average and 0.91% below its 200-day. The Dow is just above its 50-day average (+0.37%). Brazil's Ibovespa fell 0.52% and is 8.72% below its 50-day average.
Europe
| Index | Level | Day Chg | Day Chg % | Source |
|---|---|---|---|---|
| Euro STOXX 600 | 658.32 | +1.80 | +0.27% | yfinance ^STOXX |
| CAC 40 | 8,278.59 | +45.30 | +0.55% | yfinance ^FCHI |
| DAX | 26,347.45 | +80.26 | +0.31% | yfinance ^GDAXI |
| FTSE 100 | 10,751.59 | −31.28 | −0.29% | yfinance ^FTSE |
| SMI (Swiss) | 15,037.94 | +91.79 | +0.61% | yfinance ^SSMI |
European data reflects the 10 Nov 2026 close.
The STOXX 600 closed 0.77% below its record of 663.41 after trading at 661.56 in the morning (ZeroHedge), and is 2.72% above its 50-day average. Switzerland's SMI rose 0.61% and is within 0.5% of its record. The DAX is 3.10% above its 50-day average and the CAC 40 3.16%; the FTSE 100 fell 0.29%, the one major European index in the red.
Asia-Pacific
| Index | Level | Day Chg | Day Chg % | Source |
|---|---|---|---|---|
| Nikkei 225 | 60,459.58 | +1,684.08 | +2.87% | yfinance ^N225 |
| Hang Seng | 24,557.04 | +108.09 | +0.44% | yfinance ^HSI |
| Shanghai Comp | 3,663.72 | +2.93 | +0.08% | yfinance 000001.SS |
| ASX 200 | 9,129.00 | +99.30 | +1.10% | yfinance ^AXJO |
| Kospi (Korea) | 5,239.13 | +220.28 | +4.39% | yfinance ^KS11 |
Asia-Pacific data reflects the 10 Nov 2026 close.
Asian chip makers rose: Tokyo Electron 4.73%, Advantest 2.36%, SK Hynix 5.2% and Samsung Electronics 3.9%, and SoftBank 13.4% (CNBC), even though it reported its first net loss in almost two years (ZeroHedge). The Kospi's 4.39% rise was strong enough to trigger a five-minute pause in buy-side programme trading during the session (CNBC), but the index is still 17.59% below its 50-day average. The Nikkei is 7.19% below its 50-day average. Taiwan's TSMC reported October revenue of NT$586.89 billion, up 59.7% on the year (CNBC). Hong Kong's Hang Seng rose 0.44% and Shanghai 0.08%. China's October exports rose 35.2% on the year and imports 41.6% (CNBC).
Emerging Markets
| Index | Level | Day Chg % | Source |
|---|---|---|---|
| MSCI EM (EEM) | 60.57 | −0.75% | yfinance EEM |
| India Nifty 50 | 25,044.65 ‡ | — | yfinance ^NSEI |
| South Africa | 67.79 | −2.02% | yfinance EZA |
Emerging-market data reflects the 10 Nov 2026 close.
‡ India Nifty 50: data reflects the 9 Nov 2026 close.
EEM's 0.75% fall is New York's valuation of emerging markets after the US inflation figures, not what its markets did: it trades in US hours, after its Asian markets had closed higher, with the Kospi up 4.39%, Taiwan's main index up about 2.3% (ZeroHedge) and the Hang Seng up 0.44%. A stronger dollar lowers the dollar value of shares priced in local currencies, and the ICE dollar index was up 0.68%. Asia's session on Wednesday will show whether local markets follow. India's markets were closed on Tuesday for Diwali-Balipratipada (Angel One), so the Nifty 50 row is Monday's close. South Africa's fund (EZA) fell 2.02%.
Index Valuations & Investment Risk
Valuation Table
| Index | Trailing P/E (live) | 50-day avg | 100-day avg | 200-day avg |
|---|---|---|---|---|
| S&P 500 | 23.9x | 24.6x | 25.5x | — |
| Nasdaq 100 | 27.8x | 28.8x | 30.2x | — |
| Euro STOXX 600 | 17.9x | 17.7x | 18.0x | — |
| CAC 40 | 16.6x | 16.6x | 17.1x | — |
| DAX | 18.1x | 18.2x | 18.4x | — |
| FTSE 100 | 16.6x | 16.2x | 17.1x | — |
| Nikkei 225 | 17.4x | 19.5x | 21.0x | — |
| MSCI EM | 14.2x | 14.1x | 15.7x | — |
Averages of the daily trailing P/E readings recorded since 1 May 2026; shown for reference only. Trailing P/E is Yahoo Finance's trailing P/E for the ETF proxies SPY, QQQ, EXSA.DE, CAC.PA, EXS1.DE, ISF.L, 1321.T and EEM, taken 18:29 CET. SPY, QQQ and EEM are priced off the 10 Nov 2026 close; the other proxies were at their close when taken.
The Nikkei fund's (1321.T) trailing P/E rose to 17.4x from 15.4x on Monday, far more than the index's 2.87% rise can explain, so the earnings figure behind the reading changed; it is used as reported.
Investment Risk Assessment for ETF Investors
United States (S&P 500 / Nasdaq ETFs)
The S&P 500's trailing P/E of 23.9x gives an earnings yield of 4.19% (1÷23.86). Against the settled 10-year Treasury yield of 4.98% (US Treasury par curve, 10 Nov) the earnings yield gap is −0.79 pp: a 10-year government bond pays more income than the index's earnings come to per dollar invested. The 10-year's 10 bp rise on the day widened the gap by about as much. Against the real 10-year yield of 2.78% (US Treasury real curve, 10 Nov) the gap is +1.41 pp; the 2.20 pp difference is the correction for company earnings growing with inflation while a bond coupon is fixed. Only the part of earnings paid out as dividends and buybacks reaches a holder as cash. The Nasdaq 100 at 27.8x has an earnings yield of 3.60%, 1.38 pp below the 10-year Treasury. The S&P 500 is 2.63% above its 200-day average and 2.02% below its 50-day. The VIX volatility index was 19.92 on 9 November (FRED VIXCLS), moderate, after Monday's rally; a Fed now expected to raise rates in December, with some chance of a half-point move, makes higher bond yields the main risk to valuations, and technology shares, the most richly valued part of the index, fell most today.
Europe (STOXX 600 / CAC 40 / DAX ETFs)
The STOXX 600 at 17.9x gives an earnings yield of 5.60% (1÷17.86); against the euro AAA 10-year yield of 3.27% (ECB YC API, 9 Nov) the euro earnings yield gap is +2.33 pp, and against today's 10-year Bund quote of 3.33% (Trading Economics) it is +2.27 pp. Against the euro-area real 10-year yield of 1.25% (AAA nominal less long-term HICP expectations, ECB SPF 2026 Q4) it is +4.35 pp. The US trades at a 33.6% premium to the STOXX 600 on trailing earnings. Part of the gap between the US and euro figures reflects different inflation and policy paths rather than different compensation for risk, although on the US figures for 10 November and the euro figures for 9 November only 18 bp of the 171 bp difference in 10-year yields is expected inflation and 153 bp is real yield. In France the CAC 40 at 16.6x yields 6.03% in earnings, 1.24 pp above the 10-year OAT at 4.79%, because French government debt pays 146 bp more than German debt. The DAX at 18.1x gives 5.54%, 2.21 pp above the Bund. ECB chief economist Philip Lane said a further rate rise may be needed in December (Trading Economics), after the 10 September move to 2.50%. For a euro investor in euro-quoted funds the quoted value carries no exchange-rate effect, but the earnings do: many STOXX 600 companies earn in dollars, and a euro 0.55% weaker today makes those earnings worth slightly more in euros.
Japan (Nikkei / TOPIX ETFs)
The Nikkei fund (1321.T) trades at 17.4x trailing earnings, an earnings yield of 5.74% (1÷17.43), 3.04 pp above the 10-year JGB at 2.70%. Today's 2.87% rise leaves the index 7.19% below its 50-day average and 2.47% below its 200-day. The Bank of Japan raised its rate to 1.25% on 18 September and held it on 30 October, and its chief economist signalled on Monday a likely rise in December (Trading Economics). The yen weakened to 158.79 per dollar, down 0.56%, as the dollar rose against every major currency; for a euro investor an unhedged Nikkei fund carries that yen exposure in full, while a hedged share class removes it but pays the difference between euro and yen short-term rates.
Emerging Markets (MSCI EM ETFs)
EEM trades at 14.2x trailing earnings, an earnings yield of 7.03% (1÷14.22) and a 40.4% discount to the S&P 500. The fund is 7.26% below its 50-day average, with Korea's Kospi, a large weight, 17.59% below its own despite today's 4.39% rise. Higher US yields and a stronger dollar, as today, raise the cost of dollar debt for emerging economies and the pressure on their central banks to keep rates high, effects that weigh on local share prices whatever the investor's home currency; the currency conversion itself largely cancels for a euro holder, since the euro also fell against the dollar today.
Overall Risk Score: - United States: High valuation risk / low margin of safety. A negative nominal earnings yield gap that widens with every rise in the 10-year yield, which settled at 4.98% after a 10 bp rise, and a Fed expected to raise rates in December. - Europe: Moderate. Positive earnings yield gaps on both measures and a P/E well below the US, but the STOXX 600 is 0.77% below its record and Bund and gilt yields followed Treasuries up today. - Japan: Moderate. A P/E of 17.4x, higher than last week on a changed earnings figure, and a Bank of Japan that may raise rates in December. - Emerging markets: Moderate. The cheapest of the four on trailing earnings, with higher US yields and a stronger dollar the main pressure today.
US Economic Indicators (FRED - authoritative)
| Indicator | Current | Prior | Delta | Reference Date | FRED Series |
|---|---|---|---|---|---|
| CPI YoY % | 3.72% | 3.35% | +0.36 pp | Sep 2026 (prior Aug) | CPIAUCSL |
| Core CPI YoY % | 2.57% | 2.45% | +0.12 pp | Sep 2026 (prior Aug) | CPILFESL |
| Unemployment Rate | 4.1% | 4.2% | −0.10 pp | Oct 2026 (prior Sep) | UNRATE |
| Nonfarm Payrolls | +165k | +60k | +105k | Oct 2026 (prior Sep), monthly chg | PAYEMS |
| 10Y TIPS Real Yield | 2.78% | 2.66% | +12 bp | 10 Nov 2026 (prior 9 Nov) | DFII10 (US Treasury real curve) |
The CPI rows are September's, the latest FRED holds. October's report, published today, gave monthly changes only (headline +0.4%, core +0.3%), because October 2025 prices were not collected during last year's shutdown and no year-on-year rate could be calculated (CNBC).
Other economic releases today (web search)
| Release | Actual | Consensus | Prior | Note |
|---|---|---|---|---|
| US CPI MoM (Oct) | 0.4% | 0.3% | 0.6% | above consensus; energy +0.7%, food +0.5%, shelter +0.3% and over 30% of the rise; no year-on-year rate published because October 2025 data were not collected during the shutdown (CNBC) |
| US core CPI MoM (Oct) | 0.3% | 0.2% | 0.3% | above consensus; the level Governor Waller had said could justify a half-point December rise (CNBC) |
| US NFIB small business optimism (Oct) | 97.8 | 98.2 | — | below consensus (ZeroHedge) |
| China exports YoY (Oct) | 35.2% | — | — | imports +41.6%, trade surplus 105.3 billion dollars (CNBC) |
Shelter rose 0.3% and accounted for more than 30% of October's headline increase; energy rose 0.7% and food 0.5% (CNBC). The core reading of 0.3% matched the level Governor Waller had named as the case for a half-point rise, and on the settled curve the 1-year and 2-year yields rose most, 18 bp and 17 bp against 10 bp at the 10-year, as markets priced more Fed rises over the next year or two.
Fixed Income & Bond Analysis
Policy Rates
| Central Bank | Rate | Source |
|---|---|---|
| Fed Funds (upper) | 4.00% | FRED DFEDTARU (10 Nov 2026) |
| Fed Funds (lower) | 3.75% | FRED DFEDTARL (10 Nov 2026) |
| Effective FFR | 3.88% | FRED DFF (9 Nov 2026) |
| ECB Deposit Rate | 2.50% | FRED ECBDFR (10 Nov 2026) |
| BOJ Policy Rate | 1.25% | web search (raised to 1.25% on 18 Sep 2026, held on 30 Oct 2026) |
| BOE Bank Rate | 4.00% (SONIA 3.99%) | FRED IUDSOIA (6 Nov 2026); web search (Trading Economics: raised 25 bp to 4.00% on 5 Nov 2026) |
The Fed's range is 3.75% to 4.00%, held at the October meeting by a 10 to 2 vote (CNBC), ahead of its 8 to 9 December decision. Dallas Fed President Lorie Logan said she sees the need for two more quarter-point rises and then a pause (CNBC). The Bank of England raised Bank Rate to 4.00% on 5 November; SONIA was 3.99% on 6 November, just under the new rate.
Government Bond Yields
| Country | 2Y Yield | 10Y Yield | 30Y Yield | Day Chg (10Y) | Source |
|---|---|---|---|---|---|
| USA | 4.73% | 4.98% | 5.35% | +10 bp | US Treasury par curve (10 Nov 2026) |
| Germany | 3.09% | 3.33% | 3.67% | +6 bp | web (Trading Economics, 10 Nov 2026 intraday) |
| France | 3.57% | 4.79% | 5.33% | +4 bp | web (Trading Economics, 10 Nov 2026 intraday) |
| UK | 4.89% | 5.23% | 5.66% | +9 bp | web (Trading Economics, 10 Nov 2026 intraday) |
| Japan | 1.79% | 2.70% | 3.88% | +2 bp | web (Trading Economics, 10 Nov 2026 intraday) |
| Italy | — | 4.38% | — | +7 bp | web (Trading Economics, 10 Nov 2026 intraday) |
The USA day change is against the 9 Nov 2026 curve from the same feed.
Yield Curve Spreads (US Treasury par curve, 10 Nov 2026): - 10Y-2Y spread: +25 bp, flat (within the ±25 bp flat band), −7 bp on the day. - 10Y-3M spread: +68 bp, positive, no recession signal, +4 bp on the day.
OAT-Bund Spread: 146 bp (10-year OAT 4.79% against Bund 3.33%, Trading Economics, 10 Nov 2026 intraday).
The US inflation figures pushed yields up across Europe, reversing early falls: the 2-year Bund rose 9 bp and the 10-year 6 bp, so the short end rose more than the long. In the UK the 2-year gilt rose 13 bp to 4.89% and the 10-year 9 bp to 5.23%; Bank of England officials have signalled further rises, and third-quarter GDP on Thursday is the next test for gilts (Trading Economics). The 10-year OAT rose less than the Bund, 4 bp, so the OAT-Bund spread narrowed to 146 bp from 148 bp on Monday. Italy's 10-year rose 7 bp to 4.38%, 105 bp above the Bund. In the US the curve flattened: the 2-year rose 17 bp to 4.73% and the 10-year 10 bp to 4.98%, so the gap between them narrowed 7 bp to 25 bp, the edge of the flat band, and the 30-year rose 9 bp to 5.35%. Expected Fed rises weigh most on maturities of one to three years, which is why they moved most; the 3-month bill rose only 6 bp. Japan's 10-year yield rose 2 bp to 2.70%.
Yield Curve Charts
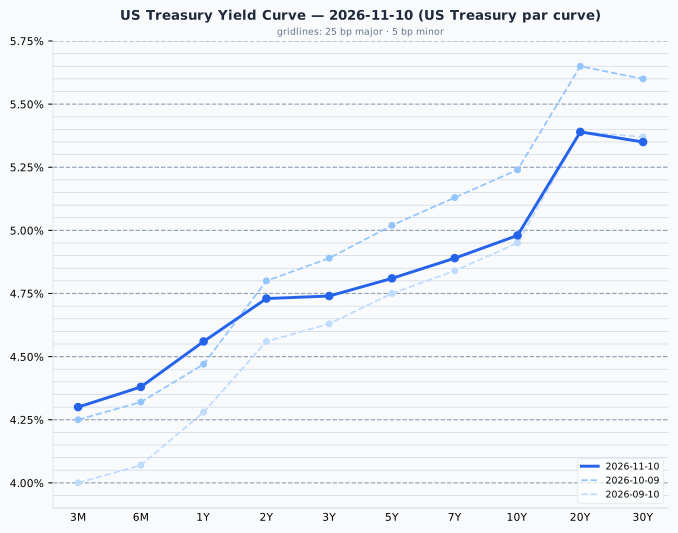
US Treasury par curve, 10 Nov 2026: 3M 4.30%, 6M 4.38%, 1Y 4.56%, 2Y 4.73%, 3Y 4.74%, 5Y 4.81%, 7Y 4.89%, 10Y 4.98%, 20Y 5.39%, 30Y 5.35%; 2-to-10 slope +25 bp. Day change against the 9 Nov 2026 curve: 3M +6 bp, 6M +12 bp, 1Y +18 bp, 2Y +17 bp, 3Y +16 bp, 5Y +14 bp, 7Y +13 bp, 10Y +10 bp, 20Y +10 bp, 30Y +9 bp. The 3-month bill at 4.30% is 42.5 bp above the Fed Funds midpoint of 3.875%.
The 10 November curve rises from 4.30% at three months to 5.39% at 20 years, with the 30-year slightly lower at 5.35%. Since the 9 October curve it has fallen by 7 bp at the 2-year and 26 bp at the 10-year, while the 3-month bill is 5 bp higher, so the curve is lower and flatter than a month ago; Tuesday's 10 bp rise took back more than a quarter of the month's fall at the 10-year.
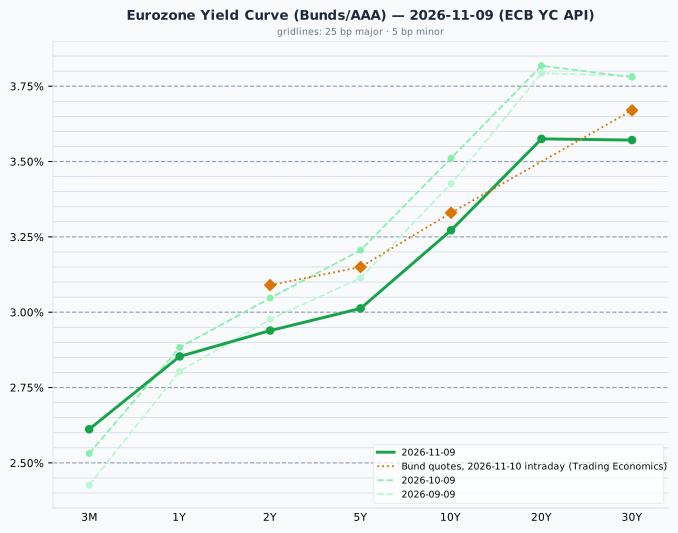
Euro area AAA government curve, 9 Nov 2026 (ECB YC API): 3M 2.61%, 1Y 2.85%, 2Y 2.94%, 5Y 3.01%, 10Y 3.27%, 20Y 3.58%, 30Y 3.57%; 2-to-10 slope +33 bp. Today's Bund quotes (Trading Economics, 10 Nov 2026), overlaid, differ from the plotted 9 Nov 2026 curve by at most 15 bp, at the 2Y (3.09% against 2.94%); the curve is the ECB's fitted AAA euro-area composite and the quotes are on-the-run Bunds, which sit a few basis points apart by construction, so only a gap well beyond that is a day move.
The euro AAA curve rises from 2.61% at three months to 3.58% at 20 years. Since the 9 October curve the 10-year has fallen 24 bp and the 2-year 11 bp while the 3-month rate rose 8 bp, so the euro curve has also flattened over the month; today's Bund quotes, plotted above it, sit highest at the 2-year, where the day's rise was largest.
Credit Markets (from FRED - authoritative)
| Market | OAS | Obs. date | vs prior obs | Series ID |
|---|---|---|---|---|
| US Investment Grade | 91 bp | 9 Nov 2026 | −2 bp | BAMLC0A0CM |
| US High Yield | 334 bp | 9 Nov 2026 | −8 bp | BAMLH0A0HYM2 |
| Euro High Yield | 340 bp | 9 Nov 2026 | −9 bp | BAMLHE00EHYIOAS |
Change is 9 Nov 2026 vs 6 Nov 2026. Credit spreads are the 9 November close; today's session is not in them yet.
US high yield at 334 bp and investment grade at 91 bp are both in their normal ranges (300 to 500 bp and 80 to 150 bp); euro high yield is 340 bp. The 9 November figures show Monday's rally, which tightened US high yield by 8 bp, and not today's fall.
Real Yields (US and Euro Area)
| Region | Nominal 10Y | Expected inflation | Real 10Y | How the real yield is obtained |
|---|---|---|---|---|
| United States | 4.98% (US Treasury par curve, 10 Nov 2026) | 2.20% (residual: nominal − real) | 2.78% (US Treasury real curve, 10 Nov 2026) | Measured. TIPS trade, so the market quotes a real yield directly; expected inflation is the residual (the breakeven) |
| Euro area | 3.27% (ECB YC API, 9 Nov) | 2.02% (ECB SPF, 2026 Q4, measured) | 1.25% (residual: nominal − expected) | Constructed. No euro inflation-linked benchmark is published, so a survey expectation is subtracted from the nominal yield |
The US real yield of 2.78% is a market price, quoted on inflation-protected Treasuries, and the 2.20% expected inflation is derived from it; the euro figure works the other way, subtracting a survey's 2.02% expected inflation from the AAA yield, so the euro real yield of 1.25% is the softer of the two. Two mismatches apply: the US breakeven includes a premium investors demand for inflation risk, which a survey does not, and the survey's five-year horizon is shorter than the bond's ten years. On the US figures for 10 November and the euro figures for 9 November, the 171 bp gap between US and euro 10-year yields is 18 bp of expected inflation and 153 bp of real yield. The US real yield rose 12 bp from 2.66% on 9 November, while the breakeven fell 2 bp.
The US–euro real rate gap is not an investment opportunity
The US real yield has exceeded the euro one in every quarter since 2014, by 1.52 pp on average, and today's 153 bp is above that mean. It is a structural feature (US trend growth, euro-area savings, Bund scarcity, US fiscal supply), not a trade a EUR-based reader can capture: hedging the currency removes it, because the forward rate is set from the same interest differential, and holding Treasuries unhedged is a dollar bet rather than a bond decision. A real yield is real in its own currency; a US real yield of 2.78% is that much above US inflation, which is not a real return for someone who spends euros. The gap is stated here as a description of relative policy stance and growth expectations, and no portfolio conclusion is drawn from it.
Bond Portfolio Implications
A 10 bp rise in yields is an ordinary day's move. At the 10 Nov 2026 par yields it costs:
| Maturity | Yield | Modified duration | Loss for a 10 bp rise | Months of coupon lost |
|---|---|---|---|---|
| 2-year | 4.73% | 1.89 | 0.19% | 0.5 |
| 10-year | 4.98% | 7.80 | 0.78% | 1.9 |
| 30-year | 5.35% | 14.86 | 1.47% | 3.3 |
Months of coupon lost is the loss divided by one month of coupon (yield ÷ 12) on a par bond.
Today's 10 bp rise at the 10-year cost a holder about 0.8%, or 1.9 months of coupon.
The settled 10-year Treasury at 4.98% pays 0.79 pp more than the S&P 500's earnings yield of 4.19%, and the 2-year at 4.73% pays 0.54 pp more; a bond buyer can lock in that income today, while an equity holder accepts the index's earnings yield, of which only the dividend and buyback part arrives as cash. On a real basis the comparison reverses (earnings yield 1.41 pp above the 2.78% real yield), because company earnings rise with inflation and a coupon does not. Tuesday's 17 bp rise at the 2-year cost a holder about 0.3%, less than half the 10-year's 0.8% loss on a 10 bp rise, because the 2-year's duration of 1.89 is about a quarter of the 10-year's 7.80. With a December Fed rise now fully priced and some chance of a half-point move, short maturities keep most of the income with far less exposure to a further surprise; the long end pays 62 bp more at 30 years for nearly eight times the 2-year's loss on a 10 bp rise.
Currencies & Commodities
Currencies (Yahoo Finance live quotes)
| Pair | Rate | Day chg % | Source |
|---|---|---|---|
| EUR/USD | 1.1157 | −0.55% | yfinance (18:29 CET) |
| USD Index (DXY, ICE) | 102.35 | +0.68% | yfinance (18:19 CET) |
| USD/JPY | 158.79 | +0.56% | yfinance (18:29 CET) |
| GBP/USD | 1.3331 | −0.85% | yfinance (18:29 CET) |
| USD/CHF | 0.8262 | +0.87% | yfinance (18:29 CET) |
FX quotes as of 18:29 CET; day change vs the previous 17:00 ET close.
Commodities (Yahoo Finance front-month futures)
| Commodity | Price | Day Chg % | Ticker | Source |
|---|---|---|---|---|
| Brent Crude ($/bbl) | 91.49 | −1.17% | BZ=F | yfinance (BZF27, Jan) |
| WTI Crude ($/bbl) | 86.04 | −0.93% | CL=F | yfinance (CLZ26, Dec) |
| Gold ($/oz) | 4,030.20 | −2.05% | GC=F | yfinance (GCZ26, Dec) |
| Silver ($/oz) | 51.225 | −2.79% | SI=F | yfinance (SIZ26, Dec) |
| Copper ($/lb) | 6.2345 | −1.73% | HG=F | yfinance (HGZ26, Dec) |
| Nat Gas ($/MMBtu) | 3.296 | +2.42% | NG=F | yfinance (NGZ26, Dec) |
Day changes are settlement-to-settlement: 10 Nov 2026 settlement vs 9 Nov 2026 settlement. Prices are the 10 November settlements of the contracts named.
Brent's January contract (BZF27), the same contract as Monday's table, traded between $89.21 and $92.84 during the European morning (ZeroHedge) and settled at $91.49, down 1.17%, near the middle of its 52-week range of $58.72 to $126.10. Brent was down 6.9% this week by early Tuesday (CNBC), after a 13.3% fall on the same contract the week before (Trading Economics). WTI's December contract (CLZ26) settled at $86.04, down 0.93%, within a 52-week range of $54.98 to $119.48. Gold was already 1.5% lower before the inflation figures (ZeroHedge) and settled 2.05% lower at $4,030.20, 27.9% below its all-time high of $5,586.20 set on 29 January 2026 and $150.90 above its 52-week low of $3,879.30. Silver fell 2.79% to $51.225, 57.8% below its all-time high of $121.30 from the same day. Copper fell 1.73% to $6.2345 per pound, 8.7% below its all-time high of $6.83 set on 22 September. Natural gas rose 2.42% to $3.296, near the low end of its 52-week range of $2.483 to $7.827.
Sector & Theme Highlights
US sectors (Select Sector SPDR funds): technology (XLK) fell 1.15%, the largest move among the eleven sector funds and the main reason the S&P 500 fell. Financials (XLF) rose 0.52%, energy (XLE) 0.44%, communication services (XLC) 0.37% and health care (XLV) 0.29%; the remaining six funds (materials, consumer staples, utilities, real estate, industrials and consumer discretionary) moved by 0.17% or less.
Chips: Monday's US rally, when the Philadelphia semiconductor index rose 7% (CNBC), carried into Asia and Europe on Tuesday: Korea's SK Hynix and Japan's Tokyo Electron, and in Europe Infineon (+4.8%), ASM International (+2.4%) and BE Semiconductor (+2.9%) all rose (CNBC). Infineon forecast revenue of about €20 billion for 2027, after €16.35 billion in its 2026 financial year (CNBC). In New York chip shares kept most of Monday's gain, the Philadelphia semiconductor index down 0.35% (Yahoo Finance), while Nvidia fell about 5.5% (YourNews).
Rates and the Fed: the October inflation figures moved the debate from whether the Fed raises rates in December to by how much. Technology, where Nvidia's own news added to the pressure of higher yields, fell most, while financials rose.
Oil and inflation: Brent's slide below $90 at one point eases the energy part of inflation, but October's figures showed food (+0.5%) and housing (+0.3%) costs rising as well, which oil does not address.
Top Stories (Global)
- US inflation above forecasts. October consumer prices rose 0.4% and core prices 0.3%, each 0.1 pp above forecasts; shelter accounted for more than 30% of the rise. No annual rate was published because October 2025 prices were not collected during the shutdown (CNBC).
- Fed: a December rise fully priced. After the inflation report, futures priced a quarter-point rise at the 8 to 9 December meeting, and the odds of a half-point move rose to 13.6% (CME FedWatch, via CNBC, 10 November). Governor Waller said a half-point rise should be considered, and Dallas Fed President Logan expects two more quarter-point rises (CNBC).
- Treasury yields jump, led by short maturities. The 2-year settled 17 bp higher at 4.73% and the 10-year 10 bp higher at 4.98%, just under the 5.05% of 28 October, its last close above 5% (US Treasury par curve); gilts and Bunds followed, with the 2-year gilt up 13 bp (Trading Economics).
- Nvidia down about 5.5%. The fall (YourNews) follows Monday's 4.3% drop and reports of a US probe into alleged smuggling of its AI chips and of possible new export controls (CNBC, ZeroHedge).
- Asian chip rally. The Kospi rose 4.39% and the Nikkei 2.87%; SoftBank rose 13.4% and SK Hynix 5.2%, and TSMC's October revenue rose 59.7% on the year (CNBC).
- CoreWeave results above forecasts. After the US close the AI cloud provider reported third-quarter revenue of $3.66 billion, against $3.54 billion expected, and raised its 2026 revenue forecast to $13.0 to $13.3 billion; its net loss widened to $709 million, and the shares rose about 5.7% after hours (Investing.com, Stock Titan).
- Anthropic sets its listing terms. The AI developer plans to sell 825 million shares at $70 to $78 each, raising up to $64.35 billion at a valuation of up to $1.405 trillion (CNBC).
- Brent briefly below $90. The first time since August, after President Trump said further strikes on Iran would not be needed and Qatar reported progress in US-Iran mediation (ZeroHedge).
Looking Ahead
- Wednesday 11 November: the US bond market is closed for Veterans Day while US stock exchanges trade; Asia's session will show whether the Kospi and Nikkei hold Tuesday's gains after the US fall.
- Thursday 12 November: UK third-quarter GDP, the next test for gilts after Tuesday's rise (Trading Economics).
- Friday 13 November: the second estimate of euro-area third-quarter GDP (as cited in the 5 November briefing).
- Tuesday 17 November: UK labour market figures (ONS).
- Later in November: the US PCE price index, which Dallas Fed President Logan said could also rise (CNBC).
- Further out: the Fed decides on 8 to 9 December; Christine Lagarde leaves the ECB on 7 February 2027.
Market closures - The US bond market, not stocks, Wednesday 11 Nov 2026: Veterans Day. - Further out: Brazil 20 Nov 2026 (Black Awareness Day); Japan 23 Nov 2026 (Labour Thanksgiving Day). - No Indian holiday data is available here, so Indian closures are not checked.
Data sources: US Treasury par and real curves (10 Nov 2026) and FRED (policy rates, VIX, credit spreads, macro); ECB YC API (AAA curve, 9 Nov 2026) and ECB SPF (2026 Q4); equity indices, ETF P/E proxies, commodity futures, live yields and FX via Yahoo Finance (taken 18:29 CET, with the Americas indices, EEM, EZA and the commodity settlements at the 10 Nov 2026 close); European, UK and Japanese bond yields, economic releases and news via web search (Trading Economics, CNBC, ZeroHedge, Yahoo Finance, Investing.com, Angel One).