2026 10 05
Global Financial Briefing — Monday, 5 October 2026
Figures reflect the 5 Oct close wherever close data exists. FX quotes and the French, UK, Japanese and Italian bond yields are evening quotes; other figures are dated inline. The US Treasury curve and the euro AAA curve are the 5 Oct closes.
Market Overview
Brazil's presidential election produced the largest move in global markets today. In Sunday's first round, senator Flávio Bolsonaro took 47.03% of valid votes against 45.16% for President Luiz Inácio Lula da Silva, a better showing than private polls had suggested, and the two meet in a runoff on 25 October (Wikipedia's count of the official results; MarketScreener). Brazil's Ibovespa closed up 7.70% at 206,912, its largest daily gain in more than six years and its first close above 200,000, well above its previous record close of 199,355, after touching an intraday record of 209,605.70 (InfoMoney, CNN Brasil). Early in the session Banco do Brasil was up 12.9% and Petrobras 7.5% (MarketScreener, Revista Oeste), and the dollar closed down 4.12% against the real at 5.00 reais (CNN Brasil). For a foreign holder the gain is larger still: a Brazil fund priced in dollars or euros gains from both the rise in share prices and the rise in the real.
In New York, shares rose while Treasury yields rose too. The S&P 500 closed up 0.66% at 7,773.95 and the Dow up 0.18%, while the Nasdaq 100 rose 0.87% to a record close of 31,076.44; the Nasdaq Composite also closed at a record, led by shares tied to artificial intelligence (CNBC). An analyst quoted by Yahoo Finance said growth shares were rising because Friday's weak September jobs report, which showed only 29,000 jobs added, had made a Fed rate rise this month less likely. The analyst added that the rise came even though the Treasury yield used to value those shares remains exceptionally high. Growth shares are valued mostly on profits expected years from now, and a high yield lowers what those distant profits are worth today. The 10-year Treasury yield closed at 5.31% and the 30-year at 5.66%, each up 3 bp on the day (US Treasury par curve, 5 Oct). ISM's survey of service companies, released at 10:00 ET, showed activity still growing in September, with the headline index at 54.9 after 55.4 in August, and its index of prices paid by those companies rose to 74.0, the highest since July 2022 (ISM).
Europe was mixed. The STOXX 600 rose 0.36%, the DAX 0.09% and the FTSE 100 0.34%, while the CAC 40 fell 0.80%, the weakest of the major indices, and the euro fell 0.45% to $1.1207, in line with the dollar's rise against the other major currencies. The CAC 40's fall came amid doubts, reported by FXStreet, that France's minority government can cut its deficit to the EU's 3% limit by 2029, as Finance Minister Roland Lescure has proposed, without large concessions in parliament. In Spain, Prime Minister Pedro Sánchez called an early general election for 29 November after Congress rejected two of his government's housing decrees (Euronews, CNBC); Madrid's index nonetheless rose 1.1% (Il Sole 24 Ore). Government bond yields rose: the German 10-year touched 3.41% in the morning, its lowest since early September, before rising to 3.49% in afternoon quotes, up 4 bp on the day, and the UK 10-year gilt rose 5 bp to 5.43% (Trading Economics). In Asia, the Nikkei rose 2.40% to 69,946.86, led by shares linked to artificial intelligence, with SoftBank Group up nearly 4% (Invezz); mainland China and South Korea were closed for holidays. Brent crude settled 1.89% lower at $100.32 a barrel, a day after OPEC+ kept its November output targets unchanged.
Global Indices Snapshot
Americas
| Index | Level | Day Chg | Day Chg % | Source |
|---|---|---|---|---|
| S&P 500 | 7,773.95 | +51.23 | +0.66% | yfinance ^GSPC |
| Nasdaq 100 | 31,076.44 | +268.51 | +0.87% | yfinance ^NDX |
| Dow Jones | 51,267.90 | +90.94 | +0.18% | yfinance ^DJI |
| Brazil IBOV | 206,911.89 | +14,797.34 | +7.70% | yfinance ^BVSP |
Americas data reflects the 5 Oct close.
The Ibovespa's 7.70% rise to a record 206,911.89 is measured from its 2 October close of 192,114.55 (InfoMoney, CNN Brasil). The index is now 16.1% above its 200-day average of 178,248. The Nasdaq 100's close is above its previous 52-week high of 31,017.53, a new record. The Dow remains 2.71% below its 50-day average while the S&P 500 is 1.42% above its own, so the Dow has lagged the broader market over recent weeks.
Europe
| Index | Level | Day Chg | Day Chg % | Source |
|---|---|---|---|---|
| Euro STOXX 600 | 633.62 | +2.27 | +0.36% | yfinance ^STOXX |
| CAC 40 | 7,834.10 | −63.09 | −0.80% | yfinance ^FCHI |
| DAX | 25,254.21 | +23.01 | +0.09% | yfinance ^GDAXI |
| FTSE 100 | 10,497.94 | +35.99 | +0.34% | yfinance ^FTSE |
| SMI (Swiss) | 13,703.53 | +42.61 | +0.31% | yfinance ^SSMI |
European data reflects the 5 Oct 2026 close.
The CAC 40 was the only major European index to fall. It closed 6.11% below its 50-day average of 8,344 and 4.90% below its 200-day average of 8,238, and 10.5% below its 52-week high of 8,755.03, the widest gap of the five. Italy's FTSE MIB rose 0.66% to 50,818 (Il Sole 24 Ore).
Asia-Pacific
| Index | Level | Day Chg | Day Chg % | Source |
|---|---|---|---|---|
| Nikkei 225 | 69,946.86 | +1,637.40 | +2.40% | yfinance ^N225 |
| Hang Seng | 24,040.34 | +68.05 | +0.28% | yfinance ^HSI |
| Shanghai Comp | 3,842.19 ‡ | — | — | yfinance 000001.SS |
| ASX 200 | 8,686.40 | +4.30 | +0.05% | yfinance ^AXJO |
| Kospi (Korea) | 7,003.74 † | — | — | yfinance ^KS11 |
Asia-Pacific data reflects the 5 Oct 2026 close.
‡ Shanghai Comp: data reflects the 30 Sep 2026 close.
† Kospi (Korea): 5 Oct 2026 is National Foundation Day (Korea), market closed; the level is the 2 Oct 2026 close.
The Nikkei's 2.40% rise was led by SoftBank Group, which holds a large stake in OpenAI, and by the chip-equipment makers Tokyo Electron and Advantest (Invezz). It left the index 6.66% above its 50-day average and 3.96% below its 52-week high of 72,831.73. Mainland Chinese markets remain shut for the National Day holiday and reopen on 8 October, so Shanghai's level is its 30 September close. Hong Kong rose 0.28% after Friday's 2.60% fall.
Emerging Markets
| Index | Level | Day Chg % | Source |
|---|---|---|---|
| MSCI EM (EEM) | 68.73 | +1.57% | yfinance EEM |
| India Nifty 50 | 22,555.75 | +0.60% | yfinance ^NSEI |
| South Africa | 63.17 | −0.03% | yfinance EZA |
MSCI EM (EEM) and South Africa reflect the 5 Oct close.
EEM rose 1.57% in New York, more than the Asian markets that make up most of the MSCI EM index: Hong Kong rose 0.28% and India 0.60%, while mainland China and Korea were closed. Brazil, which trades during New York hours, is the one large member whose move today is fully in EEM's price, and its shares and currency both jumped. Taiwan's and Korea's next sessions will show whether the rest of the index follows.
Index Valuations & Investment Risk
Valuation Table
| Index | Trailing P/E (live) | 50-day avg | 100-day avg | 200-day avg |
|---|---|---|---|---|
| S&P 500 | 25.0x | 25.6x | 26.4x | — |
| Nasdaq 100 | 30.8x | 30.3x | 31.8x | — |
| Euro STOXX 600 | 17.5x | 18.0x | 18.2x | — |
| CAC 40 | 16.0x | 17.1x | 17.3x | — |
| DAX | 17.9x | 18.6x | 18.5x | — |
| FTSE 100 | 14.9x | 17.1x | 17.5x | — |
| Nikkei 225 | (not retrieved) | — | — | — |
| MSCI EM | 14.6x | 15.9x | 16.8x | — |
Averages of the daily trailing P/E readings recorded since 1 May 2026 (n = 103); shown for reference only. Trailing P/E is Yahoo Finance's trailing P/E for the ETF proxies SPY, QQQ, EXSA.DE, CAC.PA, EXS1.DE, ISF.L, 1321.T and EEM, priced at the 5 Oct close.
Nikkei 225: Yahoo Finance returned a trailing P/E of 0.23x for 1321.T today, against 22.7x on 2 October, which is a data error rather than a valuation. The row is withheld, and so are its averages, because today's reading has entered them.
Investment Risk Assessment for ETF Investors
United States (S&P 500 / Nasdaq ETFs)
The S&P 500's trailing P/E of 25.0x gives an earnings yield of 3.99% (1÷25.03). Against the 10-year Treasury at 5.31% (US Treasury par curve, 5 Oct) the earnings yield gap is −1.32 pp: a 10-year government bond pays more in income today than the index's earnings amount to per dollar invested. Against the real 10-year yield of 2.95% (US Treasury real curve, 5 Oct) the gap is +1.04 pp; the 2.36 pp between the two is the correction for company earnings growing with inflation while a bond coupon is fixed. Only the part of earnings paid out as dividends and buybacks reaches a holder as cash. The index is 0.55% below its 52-week high of 7,816.70 and 7.51% above its 200-day average (7,231). The Nasdaq 100 at 30.8x has an earnings yield of 3.24%, 2.07 pp below the 10-year Treasury, and closed at a record. Today shows the tension in these prices: shares rose on hopes that the Fed will not raise rates this month, while the 10-year yield, which sets the return investors can lock in without equity risk, closed 3 bp higher.
Europe (STOXX 600 / CAC 40 / DAX ETFs)
The STOXX 600 at 17.5x gives an earnings yield of 5.73% (1÷17.45); against the euro AAA 10-year yield of 3.50% (ECB YC API, 5 Oct) the euro earnings yield gap is +2.23 pp, and against the 10-year Bund's 3.49% (Trading Economics, 5 Oct, afternoon) it is +2.24 pp. Against the euro-area real 10-year yield of 1.47% (see Real Yields below) it is +4.26 pp. The S&P 500 trades at a 43.4% P/E premium to the STOXX 600 (25.0x against 17.5x). Part of the difference between the US and euro gaps reflects different inflation and policy paths rather than different compensation for risk, which is why the real-yield versions are shown alongside. The CAC 40 at 16.0x has an earnings yield of 6.27%, against 4.87% on the French 10-year bond, so a French saver gives up 1.40 pp of current yield by holding French bonds rather than French shares. The CAC fell 0.80% today and is the furthest of the European indices below both its 50-day and 200-day averages, with doubts over France's deficit plan weighing on French shares (FXStreet). Spain's snap election on 29 November adds political uncertainty in Spain to the fiscal doubts in France. Euro-area inflation was 3.8% in September's flash estimate, which keeps a further ECB rise in view after the 10 September move to 2.50%. A euro investor in euro-quoted funds has no exchange-rate effect on the quoted value, but the constituents earn much of their profit abroad, so moves in the euro still change the euro value of those earnings.
Japan (Nikkei / TOPIX ETFs)
Today's P/E for the Nikkei proxy could not be used (see the note under the valuation table); on 2 October it was 22.7x, close to the S&P 500's level. The index rose 2.40% today on artificial-intelligence shares. The Bank of Japan raised its policy rate to 1.25% on 18 September, its second rise this year after the 16 June move to 1.00%, and the summary of that meeting suggests another rise is possible before year-end (Trading Economics). The 10-year JGB yield was 3.10%, down 1 bp, near its highest in 30 years (Trading Economics). The yen weakened 0.16% to 158.08 per dollar. For a euro investor an unhedged Japan fund carries the yen's moves in full, so the choice between hedged and unhedged matters as much as the view on Japanese shares.
Emerging Markets (MSCI EM ETFs)
EEM trades at 14.6x, the cheapest of the indices in the table with a usable reading and a 41.6% discount to the S&P 500. Its 1.57% rise today is New York's pricing, and includes Brazil's jump, while the Asian markets that dominate the index rose less or were closed (see Emerging Markets above). A stronger dollar and higher US yields, both seen today, work against emerging markets through their economies: companies and governments with dollar debt pay more to service it, and foreign money is more inclined to leave. Those effects reach local share prices whatever currency the investor spends. For a euro holder the currency conversion itself matters less, because the euro and emerging-market currencies tend to move the same way against the dollar; today the euro fell against the dollar while the Brazilian real rose.
Overall Risk Score: - United States: High valuation risk / low margin of safety. A negative nominal earnings yield gap, an index less than 1% below its 52-week high, and a 10-year yield above 5%. - Europe: Moderate. Positive earnings yield gaps on both measures, but euro-area inflation at 3.8%, doubts over France's public finances and a snap election in Spain. - Japan: Moderate. A P/E close to the US level when last reliably measured; BOJ rate rises and the yen are the main risks. - Emerging Markets: Attractive relative valuation, with high US yields and the stronger dollar as the near-term headwinds, and Brazil now carrying a runoff on 25 October.
US Economic Indicators (FRED - authoritative)
| Indicator | Current | Prior | Delta | Reference Date | FRED Series |
|---|---|---|---|---|---|
| CPI YoY % | 3.35% | 3.30% | +0.05 pp | Aug 2026 (prior Jul) | CPIAUCSL |
| Core CPI YoY % | 2.45% | 2.47% | −0.02 pp | Aug 2026 (prior Jul) | CPILFESL |
| Unemployment Rate | 4.2% | 4.1% | +0.10 pp | Sep 2026 (prior Aug) | UNRATE |
| Nonfarm Payrolls | +29k | +133k | −104k | Sep 2026 (prior Aug), monthly chg | PAYEMS |
| 10Y TIPS Real Yield | 2.95% | 2.92% | +3 bp | 5 Oct 2026 (prior 2 Oct) | DFII10 (US Treasury real curve) |
The labour figures are Friday's September release; the CPI figures are August's, and September's are due on 14 October (BLS).
Other economic releases today (web search)
| Release | Actual | Consensus | Prior | Note |
|---|---|---|---|---|
| US ISM services PMI (Sep) | 54.9 | — | 55.4 | above 50 every month since July 2024; prices 74.0, highest since July 2022; business activity 56.5, new orders 59.8, employment 50.1 (ISM) |
| Euro area services PMI, final (Sep) | 53.0 | 53.0 | 51.6 | in line with expectations (Newsquawk) |
| Japan consumer confidence (Sep) | 35.4 | 35.3 | 35.5 | in line (Newsquawk) |
The ISM index counts how many purchasing managers report improvement, not how much: 54.9 means growth in service activity was still more widespread than decline, a little less so than in August. The prices index is not part of the headline and is the figure bond investors watch: at 74.0, far more service firms reported paying higher prices in September than lower, the most lopsided reading since July 2022. ISM reported fuel prices rising in every month since February. The employment index, at 50.1, sits almost exactly at the line between hiring and cutting, consistent with Friday's weak payrolls. In the euro area, September's final services PMI came in at 53.0, as expected, up from 51.6 in August (Newsquawk).
Fixed Income & Bond Analysis
Policy Rates
| Central Bank | Rate | Source |
|---|---|---|
| Fed Funds (upper) | 4.00% | FRED DFEDTARU (5 Oct 2026) |
| Fed Funds (lower) | 3.75% | FRED DFEDTARL (5 Oct 2026) |
| Effective FFR | 3.88% | FRED DFF (2 Oct 2026) |
| ECB Deposit Rate | 2.50% | FRED ECBDFR (5 Oct 2026) |
| BOJ Policy Rate | 1.25% | web search (raised 18 Sep 2026, effective 24 Sep) |
| BOE Bank Rate | 3.73% | FRED IUDSOIA (2 Oct 2026) |
Government Bond Yields
| Country | 2Y Yield | 10Y Yield | 30Y Yield | Day Chg (10Y) | Source |
|---|---|---|---|---|---|
| USA | 4.84% | 5.31% | 5.66% | +3 bp | US Treasury par curve (5 Oct 2026) |
| Germany | 3.00% | 3.50% | 3.77% | +4 bp | ECB YC API (5 Oct 2026) |
| France | — | 4.87% | — | — | web (Trading Economics, 5 Oct 2026 intraday) |
| UK | 4.70% | 5.43% | 5.95% | +5 bp | web (Trading Economics, 5 Oct 2026 intraday) |
| Japan | 1.92% | 3.10% | 4.24% | −1 bp | web (Trading Economics, 5 Oct 2026 intraday) |
| Italy | — | 4.66% | — | +5 bp | web (Trading Economics, 5 Oct 2026 intraday) |
The USA day change is against the 2 Oct 2026 curve from the same feed; the Germany row is the ECB's AAA euro-area curve, with its day change against the 2 Oct 2026 curve.
Yield Curve Spreads (US Treasury par curve, 5 Oct 2026): - 10Y-2Y spread: +47 bp, positive, 22 bp outside the ±25 bp flat band and under the 75 bp steep threshold, +2 bp on the day. - 10Y-3M spread: +109 bp, positive, no recession signal, unchanged on the day.
OAT-Bund Spread: 138 bp (10-year OAT 4.87% against Bund 3.49%, Trading Economics, 5 Oct 2026 intraday).
On 5 October the US 10-year, 20-year and 30-year yields each rose 3 bp, while maturities from one to five years rose 1 bp or less, so the curve steepened between two and ten years, while bill yields also rose 3 bp. In Europe, long yields also rose most: on the ECB's AAA curve the 30-year rose 5 bp, the 10-year 4 bp and the 2-year 1 bp, and the German 10-year touched 3.41% in the morning before reaching 3.49% in afternoon quotes (Trading Economics). UK gilts rose 3 to 6 bp across the curve, taking the 30-year to 5.95%. Trading Economics showed the French 10-year unchanged at 4.87% while FXStreet quoted it near 4.89% early in the day, so no French day change is given; on the afternoon quotes the OAT-Bund spread, the extra yield investors demand to hold French rather than German 10-year debt, is 138 bp. Italy's 10-year rose 5 bp to 4.66%, 117 bp above the German 10-year's 3.49%. Japan was the exception, with the 10-year JGB 1 bp lower at 3.10%.
Yield Curve Charts
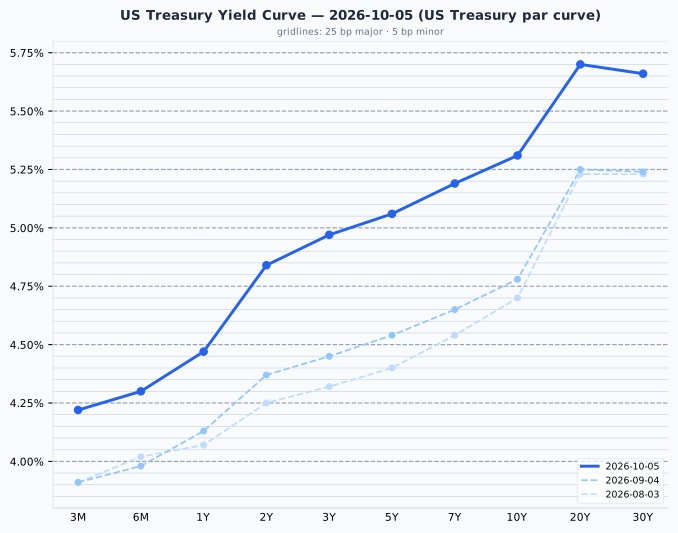
US Treasury par curve, 5 Oct 2026: 3M 4.22%, 6M 4.30%, 1Y 4.47%, 2Y 4.84%, 3Y 4.97%, 5Y 5.06%, 7Y 5.19%, 10Y 5.31%, 20Y 5.70%, 30Y 5.66%; 2-to-10 slope +47 bp. Day change against the 2 Oct 2026 curve: 3M +3 bp, 6M +3 bp, 1Y +1 bp, 2Y +1 bp, 3Y +1 bp, 5Y 0 bp, 7Y +2 bp, 10Y +3 bp, 20Y +3 bp, 30Y +3 bp. The 3-month bill at 4.22% is 34.5 bp above the Fed Funds midpoint of 3.875%.
The US curve rises from 4.22% at three months to 5.70% at 20 years, with the 30-year 4 bp below the 20-year. Since 4 September every maturity is higher, most in the middle (+54 bp at seven years, +53 bp at ten, +52 bp at three and five) and least at three months (+31 bp), with the 2-year up 47 bp and the 30-year 42 bp.
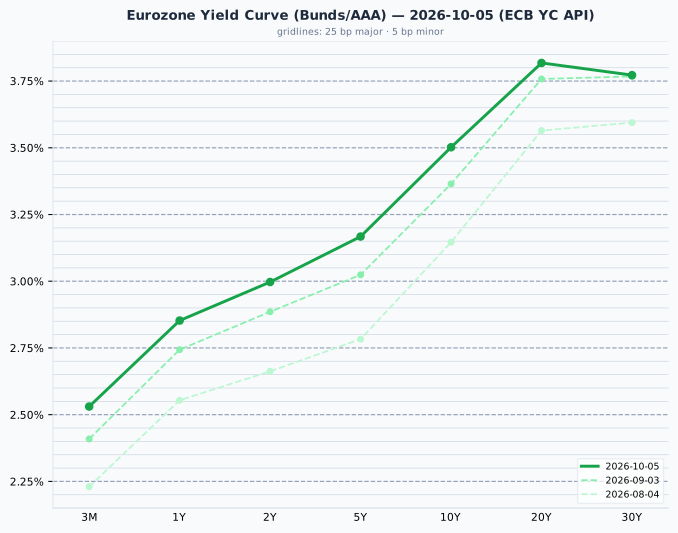
Euro area AAA government curve, 5 Oct 2026 (ECB YC API): 3M 2.53%, 1Y 2.85%, 2Y 3.00%, 5Y 3.17%, 10Y 3.50%, 20Y 3.82%, 30Y 3.77%; 2-to-10 slope +50 bp. Day change against the 2 Oct 2026 curve: 3M +1 bp, 1Y −1 bp, 2Y +1 bp, 5Y +3 bp, 10Y +4 bp, 20Y +5 bp, 30Y +5 bp.
The euro AAA curve rises from 2.53% at three months to 3.82% at 20 years. Since 3 September it has risen by 11 to 14 bp from three months to ten years, while the 20-year is 6 bp higher and the 30-year almost unchanged, so the long end has flattened.
Credit Markets (from FRED - authoritative)
| Market | OAS | Obs. date | vs prior obs | Series ID |
|---|---|---|---|---|
| US Investment Grade | 85 bp | 2 Oct 2026 | −1 bp | BAMLC0A0CM |
| US High Yield | 310 bp | 2 Oct 2026 | −14 bp | BAMLH0A0HYM2 |
| Euro High Yield | 329 bp | 2 Oct 2026 | +12 bp | BAMLHE00EHYIOAS |
Change is 2 Oct 2026 vs 1 Oct 2026. Credit spreads are the 2 October close; today's session is not in them yet.
On 2 October, the day of the weak US jobs report and a rise in US shares, US high-yield spreads narrowed by 14 bp to 310 bp, more than reversing the previous day's 12 bp widening, while euro high-yield spreads widened a further 12 bp to 329 bp. US high yield is near the bottom of the 300–500 bp range normal for it, euro high yield inside it, and US investment grade at 85 bp is inside its 80–150 bp range.
Real Yields (US and Euro Area)
| Region | Nominal 10Y | Expected inflation | Real 10Y | How the real yield is obtained |
|---|---|---|---|---|
| United States | 5.31% (US Treasury par curve, 5 Oct 2026) | 2.36% (residual: nominal − real) | 2.95% (US Treasury real curve, 5 Oct 2026) | Measured. TIPS trade, so the market quotes a real yield directly; expected inflation is the residual (the breakeven) |
| Euro area | 3.50% (ECB YC API, 5 Oct) | 2.04% (ECB SPF, 2026 Q3, measured) | 1.47% (residual: nominal − expected) | Constructed. No euro inflation-linked benchmark is published, so a survey expectation is subtracted from the nominal yield |
Only the US real yield is a market price; the euro figure is derived from a survey and is the softer of the two. Two mismatches apply when comparing them: the US breakeven includes a premium investors demand for inflation risk, which a survey does not, and the survey looks five years ahead against the bond's ten. Both legs are dated 5 October. The 181 bp gap between US and euro nominal 10-year yields splits into 32 bp of expected-inflation difference (2.36% against 2.04%) and 148 bp of real-rate difference (2.95% against 1.47%), figures rounded, so the gap is almost entirely real. The US real yield rose 3 bp on 5 October to 2.95% (against 2.92% on 2 October).
Why the US real-yield advantage is not a return a euro investor can capture
The US real yield has exceeded the euro one in every quarter since 2014, by 1.52 pp on average, and today's 148 bp is just under that mean. It is a structural feature (US trend growth, euro-area savings, Bund scarcity, US fiscal supply), not a trade a EUR-based reader can capture: hedging the currency removes it, because the forward rate is set from the same interest differential, and holding Treasuries unhedged is a dollar bet rather than a bond decision. A real yield is real in its own currency; a US real yield of 2.95% is that much above US inflation, which is not a real return for someone who spends euros. The gap is stated here as a description of relative policy stance and growth expectations, and no portfolio conclusion is drawn from it.
Bond Portfolio Implications
A 10 bp rise in yields is an ordinary day's move. At the 5 Oct 2026 par yields it costs:
| Maturity | Yield | Modified duration | Loss for a 10 bp rise | Months of coupon lost |
|---|---|---|---|---|
| 2-year | 4.84% | 1.88 | 0.19% | 0.5 |
| 10-year | 5.31% | 7.68 | 0.76% | 1.7 |
| 30-year | 5.66% | 14.36 | 1.42% | 3.0 |
Months of coupon lost is the loss divided by one month of coupon (yield ÷ 12) on a par bond. Source: US Treasury par curve, 5 October.
The 3 bp rise at the 10-year on 5 October cost a holder about 0.2%, or 0.5 months of coupon. With long yields rising faster than short ones on the day, the 30-year's 3.0 months of coupon at risk per 10 bp is the cost of its extra 0.82 pp of yield over the 2-year; the 2-year still pays 4.84% for 0.5 months of coupon at risk, so short maturities offer most of the income for far less exposure while long yields keep climbing.
Currencies & Commodities
Currencies (Yahoo Finance live quotes)
| Pair | Rate | Day chg % | Source |
|---|---|---|---|
| EUR/USD | 1.1207 | −0.45% | yfinance (18:40 CEST) |
| USD Index (DXY, ICE) | 102.25 | +0.31% | yfinance (18:31 CEST) |
| USD/JPY | 158.08 | +0.16% | yfinance (18:41 CEST) |
| GBP/USD | 1.3215 | −0.19% | yfinance (18:40 CEST) |
| USD/CHF | 0.8319 | +0.42% | yfinance (18:41 CEST) |
FX quotes as of 18:41 CEST; day change vs the previous 17:00 ET close.
The dollar rose against every currency in the table, most against the euro (−0.45%) and the Swiss franc (+0.42% for the dollar). The Brazilian real moved the other way: the dollar closed down 4.12% at 5.00 reais after the election (CNN Brasil).
Commodities (Yahoo Finance front-month futures)
| Commodity | Price | Day Chg % | Ticker | Source |
|---|---|---|---|---|
| Brent Crude ($/bbl) | 100.32 | −1.89% | BZ=F | yfinance (BZZ26, Dec) |
| WTI Crude ($/bbl) | 89.43 | −1.84% | CL=F | yfinance (CLX26, Nov) |
| Gold ($/oz) | 4,156.80 | −0.13% | GC=F | yfinance (GCZ26, Dec) |
| Silver ($/oz) | 61.300 | +1.46% | SI=F | yfinance (SIZ26, Dec) |
| Copper ($/lb) | 6.6410 | +1.40% | HG=F | yfinance (HGZ26, Dec) |
| Nat Gas ($/MMBtu) | 3.066 | +1.02% | NG=F | yfinance (NGX26, Nov) |
Day changes are settlement-to-settlement: 5 Oct settlement vs 2 Oct settlement.
The December Brent contract (BZZ26) settled at $100.32, down 1.89% from Friday's settlement, and November WTI (CLX26) at $89.43, down 1.84%, both in the upper half of their 52-week ranges ($58.72 to $126.10 for Brent, $54.98 to $119.48 for WTI). At Sunday's meeting, seven OPEC+ members led by Saudi Arabia and Russia kept their November output targets unchanged at a combined 31.01 million barrels a day, extending the pause it applied to October after a run of monthly increases (CNBC, The National). The gap between December Brent and November WTI narrowed to $10.89 from $11.14 at Friday's settlements.
Gold settled 0.13% lower at $4,156.80, 25.6% below its all-time high of $5,586.20 set on 29 January 2026, and silver 1.46% higher at $61.30, 49.5% below its all-time high of $121.30 set the same day. Copper rose 1.40% to $6.641, slightly below its all-time high of $6.83 set on 22 September. Natural gas rose 1.02% to $3.066, near the bottom of its 52-week range of $2.483 to $7.827.
Sector & Theme Highlights
US sector funds (Select Sector SPDRs, 5 Oct close): materials (XLB) +1.31% and communication services (XLC) +1.17% led, followed by energy (XLE) +1.00%, financials (XLF) +0.73%, health care (XLV) +0.72%, consumer staples (XLP) +0.63%, technology (XLK) +0.56%, utilities (XLU) +0.35%, consumer discretionary (XLY) +0.35% and industrials (XLI) +0.09%. Real estate (XLRE), down 0.34%, was the only sector to fall. Energy shares rose although crude fell.
- Brazil's election: Banco do Brasil (up 12.9% early in the session) and Petrobras (+7.5%) led a 7.7% rise in the Ibovespa to a record close, and the dollar fell 4.12% against the real (MarketScreener, Revista Oeste, InfoMoney, CNN Brasil).
- Artificial intelligence in Tokyo: SoftBank Group, Tokyo Electron and Advantest led the Nikkei's 2.40% rise (Invezz).
- European politics: doubts over France's deficit plan weighed on the CAC 40, and Spain votes in a snap election on 29 November.
- Rising long yields: the US 10-year and 30-year each rose 3 bp, and German and UK long yields rose 5 to 6 bp.
Top Stories (Global)
- Bolsonaro leads Brazil's first round. Flávio Bolsonaro took 47.03% against President Lula's 45.16%, setting up a runoff on 25 October; the Ibovespa jumped 7.7% to a record close, its largest daily gain in more than six years, and the dollar fell 4.12% against the real (Wikipedia, MarketScreener, InfoMoney, CNN Brasil).
- Spain calls a snap election. Prime Minister Pedro Sánchez set an early general election for 29 November after Congress rejected two housing decrees (Euronews, CNBC, CBC).
- US shares rise as yields climb. The S&P 500 rose 0.66% and the Nasdaq 100 0.87% to a record close, while the 10-year Treasury yield rose 3 bp to 5.31% (US Treasury par curve; CNBC, Yahoo Finance).
- US service-sector prices at a four-year high. ISM's services index eased to 54.9 in September from 55.4, but its prices index rose to 74.0, the highest since July 2022 (ISM).
- OPEC+ holds output. Seven members kept November targets unchanged at 31.01 million barrels a day; Brent settled 1.89% lower at $100.32 (CNBC, The National).
- Nikkei rises 2.40% on AI shares. SoftBank Group rose nearly 4%, with Tokyo Electron and Advantest also higher (Invezz).
- French fiscal doubts weigh on the CAC 40. The CAC 40 fell 0.80% amid doubts over France's deficit plan (FXStreet).
Looking Ahead
- Tuesday 6 October: German factory orders and euro-area retail sales for August (Newsquawk).
- Wednesday 7 October: minutes of the Fed's 16 September meeting, at which it raised its target range to 3.75–4.00% (Newsquawk).
- Thursday 8 October: account of the ECB's September meeting, read for the appetite for a further rise after September's 3.8% flash inflation; mainland Chinese markets reopen after National Day.
- Friday 9 October: Canadian September jobs report and the University of Michigan's preliminary October consumer sentiment (Newsquawk).
- Later this month: US September CPI on 14 October (BLS); Brazil's presidential runoff on 25 October; the Fed meets on 27–28 October and the Bank of Japan later in the month. Spain votes on 29 November.
Market closures - Closed today: Korea (National Foundation Day); mainland China (National Day holiday, reopening 8 October). - Korea, Friday 9 Oct 2026: Hangul Day. - Further out: Brazil 12 Oct 2026 (Nossa Senhora Aparecida); Canada 12 Oct 2026 (Thanksgiving); Japan 12 Oct 2026 (Sports Day); United States 12 Oct 2026 (Columbus Day: bond market closed, stock exchanges open).
Data sources: US Treasury par and real curves (5 Oct 2026) and FRED (policy rates, VIX, credit spreads, macro); ECB YC API (AAA curve, 5 Oct 2026) and ECB SPF (2026 Q3); equity indices, ETF P/E proxies, commodity futures, sector funds and FX via Yahoo Finance (5 Oct close, FX as of 18:41 CEST); European, UK and Japanese bond yields, economic releases and news via web search (Trading Economics, FXStreet, Il Sole 24 Ore, ISM via PR Newswire, Newsquawk, Euronews, CNBC, CBC, The National, Nairametrics, MarketScreener, Revista Oeste, InfoMoney, CNN Brasil, Invezz, Yahoo Finance, Wikipedia).