2026 10 30
Global Financial Briefing — Friday, 30 October 2026
Figures reflect the 30 Oct close wherever close data exists. FX quotes and the German, French, UK, Japanese and Italian bond yields are evening quotes; other figures are dated inline. The US Treasury curve is the 30 Oct close; the euro AAA curve is the 29 Oct curve, the latest the ECB had published.
Market Overview
Technology shares fell around the world after Intel's forecast for the fourth quarter, published after Thursday's US close, came in below expectations. Intel fell 28.58% to $65.76, its worst day since 1974 (Yahoo Finance; CNBC; FinanceFeeds), and the Philadelphia semiconductor index, which tracks the main US-listed chip companies, fell 7.20%: AMD fell 10.88%, Broadcom 5.48%, Micron 5.30% and Nvidia 4.22% (Yahoo Finance). The Nasdaq 100 fell 3.46% and the S&P 500 1.82%, while the VIX, the index of expected volatility in the S&P 500, rose 12.91% to 19.42, a moderate reading (Yahoo Finance). Investors are asking whether the heavy spending on AI will pay off, after Alphabet's 12.64% fall on Thursday and Amazon's results the same evening (Trading Economics). Amazon itself, after falling about 7% in Thursday's extended trading, closed down only 1.41%. Treasuries gained as investors sold shares: the 10-year yield settled at 4.94%, 4 bp lower on the day, and the 5-year at 4.71%, 7 bp lower (US Treasury par curve). US employment costs rose 0.8% in the third quarter, as expected, and the Chicago purchasing managers' index fell to 55.3 from 58.8, below the 56.1 forecast (Trading Economics).
The selling started in Asia. Korea's Kospi fell 3.48%, with SK hynix down 8.45% and Samsung Electronics 5.93%, and Tokyo's Nikkei 225 fell 2.12%, ending three daily rises on 27, 28 and 29 October, as chip-related shares such as Advantest, Tokyo Electron and Kioxia fell between 5% and 7% (Trading Economics). The Bank of Japan kept its rate at 1.25%, as expected, but by an 8-1 vote, with board member Hajime Takata voting for a rise to 1.5%; it said underlying inflation has reached its 2% target, which leaves a rise in December open (Trading Economics). Hong Kong went the other way: the Hang Seng rose 1.46%, led by energy, technology-services and financial shares, with energy companies helped by Sinopec's 57% jump in third-quarter profit (Trading Economics).
In Europe, the euro area grew 0.4% in the third quarter, against a 0.2% forecast, but France's economy shrank 0.1%, against a forecast of 0.1% growth, and German inflation fell to 2.8% in October from 3.3%, below the 3.0% expected, helped by a temporary cut in fuel tax (Trading Economics). German 10-year yields fell about 4 bp to 3.32%, their lowest since August, while French 10-year yields rose about 6 bp to 4.97% on the weak growth figure, higher oil prices and fiscal worries, widening the gap over Germany to 165 bp from 155 bp on Thursday's quotes (Trading Economics). European shares fell less than US ones: the STOXX 600 lost 0.36% and the DAX 0.85%, with ASML down 6.11%, while the CAC 40 was flat and Switzerland's SMI rose 0.36% to a record close. Oil rose on reports that the US was weighing renewed strikes on Iran, the January Brent contract settling 2.37% higher at $113.43, while gold settled 3.29% lower at $3,898.90 and silver 5.93% lower.
Global Indices Snapshot
Americas
| Index | Level | Day Chg | Day Chg % | Source |
|---|---|---|---|---|
| S&P 500 | 7,580.07 | −140.32 | −1.82% | yfinance ^GSPC |
| Nasdaq 100 | 28,384.85 | −1,017.66 | −3.46% | yfinance ^NDX |
| Dow Jones | 51,770.31 | −572.25 | −1.09% | yfinance ^DJI |
| Brazil IBOV | 167,921.80 | −1,264.62 | −0.75% | yfinance ^BVSP |
Americas data reflects the 30 Oct close. Day changes are against the 29 Oct close.
The S&P 500 closed 1.52% below its 50-day average, 3.70% above its 200-day and 3.37% below its 52-week high of 7,844.52. The Nasdaq 100 closed 4.74% below its 50-day average and 9.49% below its 52-week high of 31,361.37, though still 1.64% above its 200-day average. Besides the chip makers, the largest technology companies fell by smaller amounts: Microsoft 1.55%, Meta 1.53%, Alphabet 1.40% and Apple 1.23% (Yahoo Finance). Energy companies rose after results: Exxon Mobil gained 2.16% and Chevron 1.75%, both having beaten third-quarter forecasts (Trading Economics; Yahoo Finance). Smaller companies fell a little less than the S&P 500, the Russell 2000 down 1.66% to 2,811.84 (Yahoo Finance). Brazil's Ibovespa fell 0.75%, its fifth fall in the five sessions since President Lula's re-election on 25 October, and is 10.73% below its 50-day average.
Europe
| Index | Level | Day Chg | Day Chg % | Source |
|---|---|---|---|---|
| Euro STOXX 600 | 646.75 | −2.36 | −0.36% | yfinance ^STOXX |
| CAC 40 | 7,969.42 | −0.58 | −0.01% | yfinance ^FCHI |
| DAX | 25,818.21 | −221.47 | −0.85% | yfinance ^GDAXI |
| FTSE 100 | 10,729.78 | +7.68 | +0.07% | yfinance ^FTSE |
| SMI (Swiss) | 14,810.66 | +53.80 | +0.36% | yfinance ^SSMI |
European data reflects today's close (30 Oct).
The SMI's close of 14,810.66 is a record for the second session running, above Thursday's 14,756.86 (Yahoo Finance price history). Technology shares led European markets lower: ASML fell 6.11% (Yahoo Finance), and Infineon and STMicroelectronics also fell sharply (Trading Economics). The Euro STOXX 50 fell 1.22% (Yahoo Finance). In London, AstraZeneca rose 6.96% on results above forecasts and BP about 1.1% on its highest net income in at least five years, while NatWest fell 8.75% when its results brought no upgrade to its guidance (Yahoo Finance; Trading Economics); the FTSE 100 ended 0.07% higher. In Paris the CAC 40 was flat at 7,969.42; Crédit Agricole fell about 2% after warning about trends in France (Trading Economics). The CAC 40 is 1.08% below its 50-day average and 2.85% below its 200-day, still the only major European index below both. The DAX is 0.94% above its 50-day average and 3.01% below its 52-week high of 26,618.74.
Asia-Pacific
| Index | Level | Day Chg | Day Chg % | Source |
|---|---|---|---|---|
| Nikkei 225 | 63,290.11 | −1,369.36 | −2.12% | yfinance ^N225 |
| Hang Seng | 23,294.42 | +335.77 | +1.46% | yfinance ^HSI |
| Shanghai Comp | 3,599.02 | −52.42 | −1.44% | yfinance 000001.SS |
| ASX 200 | 8,908.10 | +16.30 | +0.18% | yfinance ^AXJO |
| Kospi (Korea) | 5,730.74 | −206.92 | −3.48% | yfinance ^KS11 |
Asia-Pacific data reflects today's close (30 Oct).
The Kospi's 3.48% fall followed a 1.24% fall on 29 October; besides SK hynix (−8.45%) and Samsung Electronics (−5.93%), Hyundai Motor fell 3.59% (Trading Economics). The index is 12.04% below its 50-day average. In Tokyo, Kioxia fell 7.1%, SoftBank Group 6%, Advantest 5.9% and Tokyo Electron 5.2%, the day after Advantest had risen about 6% on a raised forecast (Trading Economics); the Nikkei is 3.68% below its 50-day average. In Hong Kong, CNOOC rose 2.92% and PetroChina about 2.5% after Sinopec's results, and Meituan about 4.0%, while Tencent gained 1.59%, in line with the index, on the day it announced a new AI model; mainland investors had sold a net HK$24 billion of Hong Kong shares in October up to this session (Trading Economics). The Shanghai Composite fell 1.44% and is 0.69% above its 52-week low of 3,574.27. Australia's ASX 200 rose 0.18%.
Emerging Markets
| Index | Level | Day Chg % | Source |
|---|---|---|---|
| MSCI EM (EEM) | 61.04 | −2.68% | yfinance EEM |
| India Nifty 50 | 23,053.10 | +0.51% | yfinance ^NSEI |
| South Africa | 61.78 | −3.60% | yfinance EZA |
MSCI EM (EEM) and South Africa (EZA) reflect the 30 Oct New York close; the Nifty is the 30 Oct close.
EEM trades in New York after Asia has closed, so its 2.68% fall is New York's valuation of emerging markets during a session of falling chip shares. It fell less than Korea (3.48%) and more than Taiwan's Taiex (2.49%, to its lowest since 24 August; Trading Economics) and Shanghai (1.44%), while Hong Kong rose 1.46% and India's Nifty 0.51%. With the euro down 0.19% against the dollar, the fall is about 2.49% for a euro investor. EEM is 7.68% below its 50-day average. South Africa's fund fell 3.60% and is 2.51% above its 52-week low of 60.27.
Index Valuations & Investment Risk
Valuation Table
| Index | Trailing P/E (live) | 50-day avg | 100-day avg | 200-day avg |
|---|---|---|---|---|
| S&P 500 | 24.0x | 24.9x | 25.7x | — |
| Nasdaq 100 | 26.4x | 29.3x | 30.5x | — |
| Euro STOXX 600 | 17.9x | 17.7x | 18.1x | — |
| CAC 40 | 16.8x | 16.6x | 17.1x | — |
| DAX | 18.3x | 18.2x | 18.4x | — |
| FTSE 100 | 16.6x | 16.5x | 17.2x | — |
| Nikkei 225 | 16.5x | 20.4x | 21.5x | — |
| MSCI EM | 13.1x | 14.7x | 16.0x | — |
Averages of the daily trailing P/E readings recorded since 1 May 2026 (n = 122; 118 for the Nikkei proxy); shown for reference only. Trailing P/E is Yahoo Finance's trailing P/E for the ETF proxies SPY, QQQ, EXSA.DE, CAC.PA, EXS1.DE, ISF.L, 1321.T and EEM, priced off each market's 30 Oct close.
Investment Risk Assessment for ETF Investors
United States (S&P 500 / Nasdaq ETFs)
The S&P 500's trailing P/E of 24.0x gives an earnings yield of 4.17% (1÷23.99). Against the settled 10-year Treasury yield of 4.94% (US Treasury par curve, 30 Oct) the earnings yield gap is −0.77 pp: a 10-year government bond pays more income than the index's earnings come to per dollar invested. Against the real 10-year yield of 2.60% (US Treasury real curve, 30 Oct) the gap is +1.57 pp; the 2.34 pp between the two is the correction for company earnings growing with inflation while a bond coupon is fixed. Only the part of earnings paid out as dividends and buybacks reaches a holder as cash. The Nasdaq 100 at 26.4x has an earnings yield of 3.78%, 1.16 pp below the 10-year Treasury. The S&P 500 is 1.52% below its 50-day average and 3.37% below its 52-week high. This week has shown how much the index depends on confidence in AI spending: over 29 and 30 October Alphabet lost about 14% and Intel about 31%, and the chip index fell 7.20% on 30 October, while consumer staples, utilities, health care, real estate, energy and materials rose. The fall in Treasury yields on 30 October softened the blow, but core PCE inflation of 3.1% (29 Oct) still supports the December rate rise that futures priced at about 85% after the Fed's 28 October meeting (Axios, citing CME FedWatch, as cited in the 28 Oct briefing).
Europe (STOXX 600 / CAC 40 / DAX ETFs)
The STOXX 600 at 17.9x gives an earnings yield of 5.59% (1÷17.88); against the euro AAA 10-year yield of 3.37% (ECB YC API, 29 Oct) the euro earnings yield gap is +2.22 pp, and today's 10-year Bund quote of 3.32% (Trading Economics) gives +2.27 pp. Against the euro-area real 10-year yield of 1.35% (see Real Yields below) it is +4.24 pp. The S&P 500 trades at a 34.2% P/E premium to the STOXX 600 (24.0x against 17.9x). Part of the difference between the US and euro gaps reflects different inflation and policy paths rather than different compensation for risk, which is why the real-yield versions are shown alongside.
France remains the region's main risk. The CAC 40 at 16.8x has an earnings yield of 5.97% (1÷16.76), 1.00 pp above the French 10-year yield of 4.97%; the DAX at 18.3x yields 5.47%, 2.15 pp over the Bund, and the FTSE 100 at 16.6x yields 6.02%, 0.73 pp above the 10-year gilt at 5.29%. French output fell 0.1% in the third quarter and 0.1% from a year earlier, the first annual fall since the end of 2020 (Trading Economics), and French 10-year yields rose about 6 bp on a day German ones fell about 4 bp, widening the spread to 165 bp. The National Assembly votes on the revenue part of the 2027 budget on 3 November (as cited in the 27 Oct briefing). A euro investor in euro-quoted funds has no exchange-rate effect on the quoted value, but the constituents earn much of their profit abroad, so their earnings in euros still move with the currency.
Japan (Nikkei / TOPIX ETFs)
The Nikkei proxy's P/E is 16.5x (earnings yield 6.05%), 3.28 pp above the 10-year Japanese government bond at 2.77% (Trading Economics). The Bank of Japan held at 1.25% but said underlying inflation has reached 2%, raised its inflation forecast for the 2027 fiscal year to 2.6% from 2.4% and cut its growth forecast for that year to 0.7% from 0.8% (Trading Economics), so a rise in December is a live possibility. The yen strengthened 0.14% against the dollar to 157.43 and about 0.3% against the euro, so a euro investor in an unhedged Japan fund lost about 1.8% of value rather than the index's 2.12%. The Nikkei's fall was concentrated in chip-equipment and AI-related shares, the same companies that drove its rise earlier in the week.
Emerging Markets (MSCI EM ETFs)
EEM trades at 13.1x, the cheapest index in the table and a 45.4% discount to the S&P 500. Its large weights in Korean and Taiwanese chip makers made it one of today's biggest losers: SK hynix fell 8.45% and Samsung 5.93%, and Taiwan's Taiex 2.49%. A Fed rise in December would tend to draw money out of emerging markets and raise the cost of their dollar debts, whatever the investor's home currency. China's official manufacturing purchasing managers' index for October, published on Saturday 31 October, fell to 49.3 from 50.1, below the 50.0 forecast and back under the 50 line that separates growth from contraction (Newsquawk; People's Daily; China-Global South Project); it is the first new figure for the Chinese markets, which split on 30 October between Hong Kong's rise and Shanghai's fall.
Overall Risk Score: - United States: High valuation risk / low margin of safety. A negative nominal earnings yield gap, a 10-year yield near 5%, a likely December rate rise, and the largest companies now falling on doubts about whether AI spending pays. - Europe: Moderate. Positive earnings yield gaps on both measures and a P/E well below the US; French 10-year yields at 4.97%, 165 bp over Germany, after a contraction in output and with the budget not yet passed. - Japan: Moderate. A P/E of 16.5x, with a Bank of Japan that now says its inflation target has been reached. - Emerging Markets: Attractive relative valuation, with returns concentrated in Asian chip makers that fell hardest today, and Brazil still repricing its election result.
US Economic Indicators (FRED - authoritative)
| Indicator | Current | Prior | Delta | Reference Date | FRED Series |
|---|---|---|---|---|---|
| CPI YoY % | 3.72% | 3.35% | +0.36 pp | Sep 2026 (prior Aug) | CPIAUCSL |
| Core CPI YoY % | 2.57% | 2.45% | +0.12 pp | Sep 2026 (prior Aug) | CPILFESL |
| Unemployment Rate | 4.2% | 4.1% | +0.10 pp | Sep 2026 (prior Aug) | UNRATE |
| Nonfarm Payrolls | +29k | +133k | −104k | Sep 2026 (prior Aug), monthly chg | PAYEMS |
| 10Y TIPS Real Yield | 2.60% | 2.63% | −3 bp | 30 Oct 2026 (prior 29 Oct) | DFII10 (US Treasury real curve) |
The employment cost index, released today, shows labour costs rising 0.8% in the third quarter, with wages up 0.7% after 0.9% in the second quarter (Trading Economics): pay growth is easing alongside the slower hiring of September's 29,000 payroll gain.
Other economic releases today (web search)
| Release | Actual | Consensus | Prior | Note |
|---|---|---|---|---|
| BOJ policy rate | 1.25% (hold) | hold | 1.25% | 8-1 vote; Hajime Takata voted for 1.5% (Trading Economics) |
| Euro area GDP, Q3 flash, q/q | 0.4% | 0.2% | 0.6% | Ireland 5.5%, Spain and Netherlands 0.6%, Germany 0.2%, Italy 0.0%, France −0.1% (Trading Economics) |
| France GDP, Q3 preliminary, q/q | −0.1% | 0.1% | 0.0% | −0.1% y/y; exports −1.7%, investment −0.6%, household consumption +0.4% (Trading Economics) |
| Germany CPI, Oct flash, y/y | 2.8% | 3.0% | 3.3% | −0.2% m/m; HICP 2.8%; core 2.1% from 2.4%; temporary fuel tax cut (Trading Economics) |
| Tokyo CPI, Oct, y/y (ex fresh food) | 2.8% (2.6%) | — | 2.7% (2.7%) | ex food and energy 2.6% from 2.9%; consensus not retrieved (Trading Economics) |
| US employment cost index, Q3, q/q | 0.8% | 0.8% | 0.9% | wages 0.7% from 0.9%, benefits 0.9% from 1.0% (Trading Economics) |
| US Chicago PMI, Oct | 55.3 | 56.1 | 58.8 | (Trading Economics) |
The euro area beat forecasts largely because of Ireland, whose 5.5% growth Trading Economics links to AI-related investment, and because Spain and the Netherlands each grew 0.6% on consumer spending; Germany grew 0.2% despite weaker exports and investment, Italy stood still and France shrank (Trading Economics). In France, exports fell 1.7%, with shipments of transport equipment, led by aircraft, down 9.1%, and fixed investment, which covers spending by companies, households and government on buildings, machinery and software, fell 0.6% after 0.5% in the second quarter, while household spending rose 0.4% (Trading Economics). German inflation fell more than expected: energy prices rose 12.2% from a year earlier against 14.9% in September, helped by a fuel tax cut that runs from early October to the end of the year, and core inflation, which excludes food and energy, eased to 2.1% from 2.4% (Trading Economics). The Chicago index, a survey of purchasing managers in the US Midwest, remains above 50, meaning more firms reported improvement than deterioration, but fewer did so than in September.
Fixed Income & Bond Analysis
Policy Rates
| Central Bank | Rate | Source |
|---|---|---|
| Fed Funds (upper) | 4.00% | FRED DFEDTARU (30 Oct 2026) |
| Fed Funds (lower) | 3.75% | FRED DFEDTARL (30 Oct 2026) |
| Effective FFR | 3.88% | FRED DFF (29 Oct 2026) |
| ECB Deposit Rate | 2.50% | FRED ECBDFR (30 Oct 2026) |
| BOJ Policy Rate | 1.25% | web search (Trading Economics, 30 Oct 2026: held, 8-1 vote) |
| BOE Bank Rate | 3.73% | FRED IUDSOIA (SONIA proxy, 28 Oct 2026) |
The Bank of Japan held its rate at 1.25% today, where its 18 September rise put it (as cited in the 21 Oct briefing). The ECB held its deposit rate at 2.50% on 29 October, and the Fed its range at 3.75–4.00% on 28 October. The Bank of England, which held Bank Rate at 3.75% on 17 September (as cited in the 21 Oct briefing), meets on 5 November, and on 30 October money markets almost fully priced a rise at that meeting (Trading Economics).
Government Bond Yields
| Country | 2Y Yield | 10Y Yield | 30Y Yield | Day Chg (10Y) | Source |
|---|---|---|---|---|---|
| USA | 4.56% | 4.94% | 5.31% | −4 bp | US Treasury par curve (30 Oct 2026) |
| Germany | 3.01% | 3.32% | 3.68% | −4 bp | web (Trading Economics, 30 Oct 2026 intraday) |
| France | 3.67% | 4.97% | 5.47% | +6 bp | web (Trading Economics, 30 Oct 2026 intraday) |
| UK | 4.88% | 5.29% | 5.71% | 0 bp | web (Trading Economics, 30 Oct 2026 intraday) |
| Japan | 1.88% | 2.77% | 3.84% | −7 bp | web (Trading Economics, 30 Oct 2026 close) |
| Italy | — | 4.50% | — | +2 bp | web (Trading Economics, 30 Oct 2026 intraday) |
The USA row is the settled 30 Oct 2026 curve, with its day change against the 29 Oct 2026 curve from the same feed. The other rows are 30 Oct quotes, with day changes as Trading Economics reports them, rounded; Italy's 2- and 30-year yields were not retrieved.
Yield Curve Spreads (US Treasury par curve, 30 Oct 2026): - 10Y-2Y spread: +38 bp, positive, 13 bp outside the ±25 bp flat band and under the 75 bp steep threshold, +1 bp against 29 Oct. - 10Y-3M spread: +78 bp, positive, no recession signal, −2 bp against 29 Oct.
OAT-Bund Spread: 165 bp (10-year OAT 4.97% against Bund 3.32%, Trading Economics, 30 Oct 2026 intraday), against 155 bp on Thursday's quotes.
Treasuries gained across the curve on 30 October, most at three to seven years: the 3-year yield fell 8 bp to 4.65%, the 5-year and 7-year 7 bp each to 4.71% and 4.80%, the 2-year 5 bp to 4.56% and the 10-year 4 bp to 4.94%, while the 20-year and 30-year yields fell only 1 bp, to 5.34% and 5.31% (US Treasury par curve).
In Germany, the 5-year yield fell about 5 bp to 3.11%, the 2-year and 10-year about 4 bp each to 3.01% and 3.32%, and the 30-year about 3 bp to 3.68% (Trading Economics). The 10-year Bund is at its lowest since August, and fell more than 20 bp over October, as investors bought it as a safe asset during worries about France's public finances and the Middle East (Trading Economics). France went the other way: its 10-year yield rose about 6 bp to 4.97%, its 2-year about 2 bp to 3.67% and its 30-year about 4 bp to 5.47%, after the contraction in output and with oil prices rising, ahead of a presidential election next year (Trading Economics). Italy's 10-year rose about 2 bp to 4.50%, 118 bp over Germany. The UK 10-year gilt was unchanged at 5.29%, its lowest since 22 September, after the budget presented by Chancellor John Healey met the government's borrowing rules (Trading Economics). Japan's 10-year yield fell about 7 bp to 2.77% after the Bank of Japan's hold, with the fall in technology shares adding to demand for bonds (Trading Economics).
Yield Curve Charts
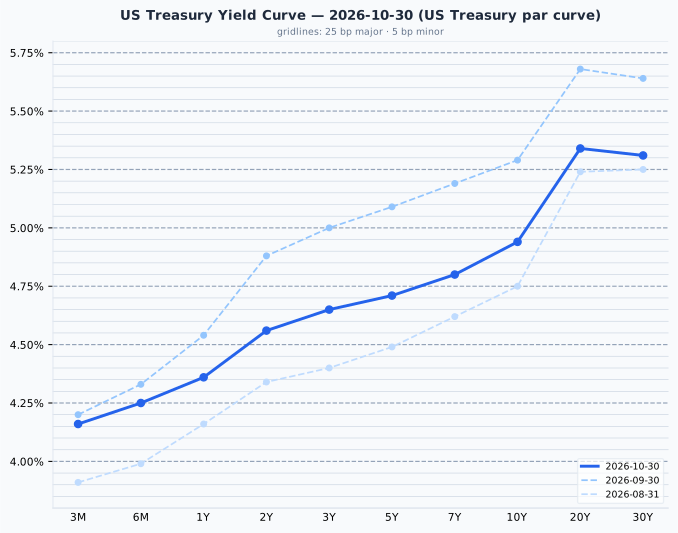
US Treasury par curve, 30 Oct 2026: 3M 4.16%, 6M 4.25%, 1Y 4.36%, 2Y 4.56%, 3Y 4.65%, 5Y 4.71%, 7Y 4.80%, 10Y 4.94%, 20Y 5.34%, 30Y 5.31%; 2-to-10 slope +38 bp. Prior curves: 30 Sep and 31 Aug 2026. The 3-month bill at 4.16% is 28.5 bp above the Fed Funds midpoint of 3.875%.
The US curve rises from 4.16% at three months to 5.34% at 20 years, with the 30-year 3 bp below the 20-year. Against 30 September the curve from two years out is 32 to 39 bp lower (the 2-year by 32 bp, the 10-year by 35 bp, the 30-year by 33 bp), so the 2-to-10 slope has narrowed from 41 bp to 38 bp; the 3-month bill's 28.5 bp gap over the Fed Funds midpoint is consistent with the December rise futures price.
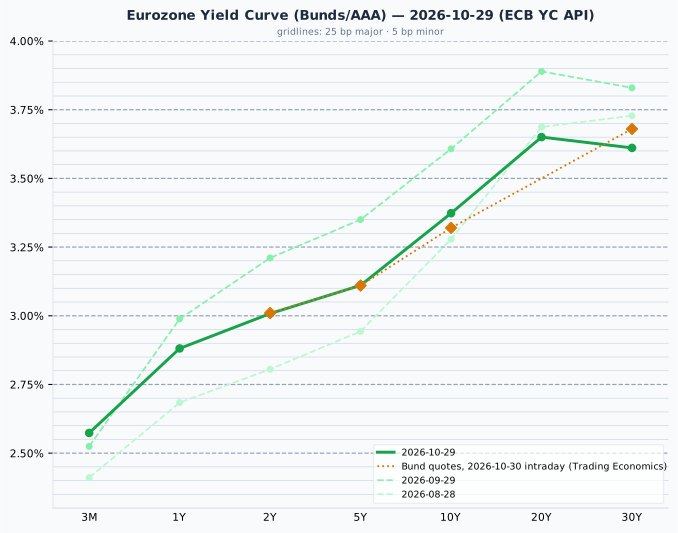
Euro area AAA government curve, 29 Oct 2026 (ECB YC API): 3M 2.57%, 1Y 2.88%, 2Y 3.01%, 5Y 3.11%, 10Y 3.37%, 20Y 3.65%, 30Y 3.61%; 2-to-10 slope +37 bp. Prior curves: 29 Sep and 28 Aug 2026. Amber markers: Bund quotes, 30 Oct 2026 intraday (Trading Economics).
The euro AAA curve rises from 2.57% at three months to 3.65% at 20 years, with the 30-year 4 bp below the 20-year; against 29 September it is 20 bp lower at two years and 23 bp lower at ten, so its slope has narrowed from 40 bp to 37 bp. Today's Bund quotes differ from the plotted 29 October curve by at most 7 bp, at 30 years (3.68% against 3.61%); the curve is the ECB's fitted AAA euro-area curve and the quotes are on-the-run Bunds, which sit a few bp apart by construction (the 30-year gap was 9 bp on Thursday's quotes), so only the 10-year's 5 bp gap, against 1 bp on Thursday, reflects today's fall.
Credit Markets (from FRED - authoritative)
| Market | OAS | Obs. date | vs prior obs | Series ID |
|---|---|---|---|---|
| US Investment Grade | 89 bp | 29 Oct 2026 | +3 bp | BAMLC0A0CM |
| US High Yield | 326 bp | 29 Oct 2026 | +12 bp | BAMLH0A0HYM2 |
| Euro High Yield | 348 bp | 29 Oct 2026 | −1 bp | BAMLHE00EHYIOAS |
Change is 29 Oct 2026 vs 28 Oct 2026. Credit spreads are the 29 October close; today's session is not in them yet.
The extra yield on lower-rated US company bonds over Treasuries widened 12 bp to 326 bp on 29 October, the day Alphabet fell 12.64%, but remains in the lower part of the normal 300–500 bp range; investment-grade spreads widened 3 bp to 89 bp, near the bottom of their 80–150 bp range. The euro lower-rated spread was little changed at 348 bp. The VIX closed at 17.20 on 29 October (FRED VIXCLS) and at 19.42 on 30 October (Yahoo Finance), both moderate readings.
Real Yields (US and Euro Area)
| Region | Nominal 10Y | Expected inflation | Real 10Y | How the real yield is obtained |
|---|---|---|---|---|
| United States | 4.94% (US Treasury par curve, 30 Oct 2026) | 2.34% (residual: nominal − real) | 2.60% (US Treasury real curve, 30 Oct 2026) | Measured. TIPS trade, so the market quotes a real yield directly; expected inflation is the residual (the breakeven) |
| Euro area | 3.37% (ECB YC API, 29 Oct 2026) | 2.02% (ECB SPF, 2026 Q4, measured) | 1.35% (residual: nominal − expected) | Constructed. No euro inflation-linked benchmark is published, so a survey expectation is subtracted from the nominal yield |
Only the US real yield is a market price; the euro figure is derived from a survey and is the softer of the two. Two mismatches apply when comparing them: the US breakeven includes a premium investors demand for inflation risk, which a survey does not, and the survey looks five years ahead against the bond's ten. The US leg is dated 30 October and the euro leg 29 October, the latest euro curve published; the survey figure is the new 2026 Q4 round, 2.02% against 2.04% in the Q3 round. The 157 bp gap between US and euro nominal 10-year yields splits into 32 bp of expected-inflation difference (2.34% against 2.02%) and 125 bp of real-rate difference (2.60% against 1.35%), figures rounded, so the gap is almost entirely real. The US real yield fell 3 bp on 30 October to 2.60%.
Why the US real-yield advantage is not a return a euro investor can capture
The US real yield has exceeded the euro one in every quarter since 2014, by 1.52 pp on average, and the 125 bp on these figures is under that mean. It is a structural feature (US trend growth, euro-area savings, the scarcity of German government bonds, heavy US government borrowing), not a return a euro-based reader can capture: hedging the currency removes it, because the forward exchange rate is set from the same interest differential, and holding Treasuries unhedged is a bet on the dollar rather than a bond decision. A real yield is real in its own currency; a US real yield of 2.60% is that much above US inflation, which is not a real return for someone who spends euros. The gap is stated here as a description of relative policy stance and growth expectations, and no portfolio conclusion is drawn from it.
Bond Portfolio Implications
A 10 bp rise in yields is an ordinary day's move. At the 30 Oct 2026 par yields it costs:
| Maturity | Yield | Modified duration | Loss for a 10 bp rise | Months of coupon lost |
|---|---|---|---|---|
| 2-year | 4.56% | 1.89 | 0.19% | 0.5 |
| 10-year | 4.94% | 7.82 | 0.78% | 1.9 |
| 30-year | 5.31% | 14.92 | 1.48% | 3.3 |
Months of coupon lost is the loss divided by one month of coupon (yield ÷ 12) on a par bond. Computed from the US Treasury par curve, 30 October.
The 10-year yield's 4 bp fall on 30 October returned a holder about 0.31%, or 0.8 months of coupon. On a day when the Nasdaq 100 fell 3.46%, the 10-year Treasury did what a bond in a mixed portfolio is meant to do and gained.
The 30-year Treasury pays 0.75 pp more than the 2-year for nearly eight times as much price movement per 10 bp. With core PCE inflation at 3.1% and futures expecting a December Fed rise, short maturities keep most of the income with far less exposure to a rise in yields, while today showed that longer maturities can still gain when shares fall sharply.
Currencies & Commodities
Currencies (Yahoo Finance live quotes)
| Pair | Rate | Day chg % | Source |
|---|---|---|---|
| EUR/USD | 1.1159 | −0.19% | yfinance (19:08 CET) |
| USD Index (DXY, ICE) | 101.98 | −0.05% | yfinance (18:58 CET) |
| USD/JPY | 157.43 | −0.14% | yfinance (19:08 CET) |
| GBP/USD | 1.3390 | +0.12% | yfinance (19:08 CET) |
| USD/CHF | 0.8239 | +0.02% | yfinance (19:08 CET) |
FX quotes as of 18:58–19:08 CET; day change vs the previous 17:00 ET close.
Currency moves were small for a day of large share moves. The euro slipped 0.19% to $1.1159 and the ICE dollar index was little changed at 101.98. The yen was little changed, up 0.14% to 157.43 per dollar, on the day the Bank of Japan held its rate and said its inflation target has been reached. The pound rose 0.12% to $1.3390 and the Swiss franc was unchanged at 0.8239 per dollar.
Commodities (Yahoo Finance front-month futures)
| Commodity | Price | Day Chg % | Ticker | Source |
|---|---|---|---|---|
| Brent Crude ($/bbl) | 113.43 | +2.37% | BZ=F | yfinance (BZF27, Jan) |
| WTI Crude ($/bbl) | 104.12 | +2.08% | CL=F | yfinance (CLZ26, Dec) |
| Gold ($/oz) | 3,898.90 | −3.29% | GC=F | yfinance (GCZ26, Dec) |
| Silver ($/oz) | 49.276 | −5.93% | SI=F | yfinance (SIZ26, Dec) |
| Copper ($/lb) | 6.4820 | −1.83% | HG=F | yfinance (HGZ26, Dec) |
| Nat Gas ($/MMBtu) | 2.898 | −1.83% | NG=F | yfinance (NGZ26, Dec) |
Day changes are settlement-to-settlement: 30 Oct 2026 settlement vs 29 Oct 2026 settlement.
Every row shows the same contract as Thursday's table, so the levels are comparable. Oil rose on reports that a senior US military commander had briefed President Trump on options for renewed strikes on Iran, on Tehran's statement that it would not soften its position although it had received a letter from Vice President JD Vance about restarting talks, and on two tanker incidents near the Strait of Hormuz; a Ukrainian strike on a Russian refinery in the Samara region added to supply worries (Trading Economics). The January Brent contract (BZF27) settled at $113.43, 2.37% above Thursday's settlement of $110.80, and the December WTI contract (CLZ26) at $104.12, 2.08% above its $102.00 settlement. January Brent is 10.05% below the 52-week high of $126.10 set by an earlier contract (range $58.72 to $126.10), and December WTI 12.86% below its $119.48 high (range $54.98 to $119.48). The December WTI contract expires on 20 November, so it is not yet near its roll.
Gold settled 3.29% lower at $3,898.90, having touched $3,879.30 during the session, a new 52-week low (Yahoo Finance); it is 30.20% below its all-time high of $5,586.20 set on 29 January 2026. Trading Economics attributes the fall to expectations that US interest rates will stay high, with energy prices keeping inflation up and a December Fed rise in prospect, and to possible selling by investors raising cash after the fall in technology shares. Silver settled 5.93% lower at $49.276, 59.38% below its all-time high of $121.30 set the same January day, and its 52-week low is $46.805. Copper settled 1.83% lower at $6.482, 5.10% below its all-time high of $6.83 set on 22 September. Natural gas settled 1.83% lower at $2.898, in the lower part of its 52-week range of $2.483 to $7.827.
Sector & Theme Highlights
US sector funds (Select Sector SPDRs, 30 Oct close): energy (XLE) led, up 1.91%, followed by consumer staples (XLP, +1.41%), utilities (XLU, +0.67%), health care (XLV, +0.45%), materials (XLB, +0.40%) and real estate (XLRE, +0.26%). Technology (XLK) was the weakest by far, down 4.89%, followed by industrials (XLI, −1.60%), communication services (XLC, −1.29%), financials (XLF, −0.76%) and consumer discretionary (XLY, −0.71%). Four of the six sectors that rose (staples, utilities, health care, real estate) are those whose earnings depend least on the economic cycle; energy gained with the oil price, and materials rose slightly.
- Chip makers sold worldwide: Intel's 28.58% fall on its weak forecast spread to AMD (−10.88%), Broadcom (−5.48%), Micron (−5.30%) and Nvidia (−4.22%) in New York, ASML (−6.11%) in Amsterdam, SK hynix (−8.45%) and Samsung (−5.93%) in Seoul, and Advantest, Tokyo Electron and Kioxia in Tokyo (Yahoo Finance; Trading Economics).
- Doubts about AI returns: after Alphabet's 12.64% fall on 29 October over spending that exceeded its operating cash flow (as cited in the 29 Oct briefing), investors are asking whether AI investment will pay off, and the selling has moved from the spenders to the suppliers of chips (Trading Economics).
- Energy holds up: Exxon Mobil and Chevron beat forecasts and rose 2.16% and 1.75%, BP reported its highest net income in at least five years, and oil rose more than 2% on the Iran reports (Trading Economics; Yahoo Finance).
- Precious metals fall with shares: gold settled 3.29% lower after touching a 52-week low during the session, and silver 5.93% lower (Yahoo Finance; Trading Economics).
- European results: AstraZeneca rose 6.96% on results above forecasts, while NatWest fell 8.75% without an upgrade to its guidance (Yahoo Finance; Trading Economics).
Top Stories (Global)
- Intel has its worst day since 1974. Intel fell 28.58% to $65.76 after forecasting fourth-quarter revenue of $15 to $16 billion, below the roughly $17 billion analysts expected (as cited in the 29 Oct briefing); only its fall of about 30% in July 1974 was larger, and the nearest since was a 26.06% fall on 2 August 2024, after Intel suspended its dividend and announced job cuts. The Philadelphia chip index fell 7.20% and the Nasdaq 100 3.46% (Yahoo Finance; CNBC; FinanceFeeds).
- Asian chip makers lead the fall. The Kospi fell 3.48%, with SK hynix down 8.45% and Samsung 5.93%, the Nikkei 2.12% and Taiwan's Taiex 2.49% (Trading Economics).
- The Bank of Japan holds, with one vote for a rise. The rate stays at 1.25% on an 8-1 vote, Hajime Takata voting for 1.5%; the bank said underlying inflation has reached its 2% target, leaving a December rise open, and the 10-year JGB yield fell about 7 bp to 2.77% (Trading Economics).
- Euro-area growth beats forecasts; France shrinks. Third-quarter GDP rose 0.4%, against 0.2% expected, led by Ireland, while France contracted 0.1%; French 10-year yields rose about 6 bp to 4.97% while German yields fell, widening the spread to 165 bp (Trading Economics).
- German inflation falls to 2.8%. October's flash figure was below the 3.0% expected, helped by a temporary fuel tax cut; core inflation eased to 2.1% (Trading Economics).
- Gold at a one-year low. Gold touched $3,879.30 during the session, its lowest in 52 weeks, and settled 3.29% lower at $3,898.90; silver settled 5.93% lower, while oil rose more than 2% on reports of US options for renewed strikes on Iran (Yahoo Finance; Trading Economics).
- Switzerland's SMI at a record. The index rose 0.36% to a record close of 14,810.66, as European shares fell much less than US ones.
Looking Ahead
- Monday 2 November: Apple reports, after the US close (as cited in the 27 Oct briefing).
- Tuesday 3 November: US midterm elections, after which President Trump has warned that strikes on Iran could resume (Trading Economics); the French National Assembly's vote on the revenue measures of the 2027 budget (as cited in the 27 Oct briefing).
- Wednesday 4 November: the euro-area flash inflation estimate for October (as cited in the 29 Oct briefing).
- Thursday 5 November: the Bank of England's decision, with a rise that money markets almost fully priced on 30 October (Trading Economics).
- Further out: Anthropic could begin marketing its listing as soon as the week of 9 November (Bloomberg, via Yahoo Finance, as cited in the 27 Oct briefing); the second estimate of euro-area third-quarter GDP on 13 November (Trading Economics); Christine Lagarde leaves the ECB on 7 February 2027.
Market closures - France 1 Nov 2026 (All Saints' Day), a Sunday, so no trading day is lost. - Brazil 2 Nov 2026 (All Souls' Day). - Japan 3 Nov 2026 (Culture Day). - No Indian holiday data is available here, so Indian closures are not checked.
Special Analysis: Intel's Share Price From the August 2024 Collapse to the October 2026 Fall
Added 31 October 2026. Intel's shares closed at $21.48 on 2 August 2024 after a 26.06% fall, reached $140.94 on 22 June 2026 and fell back to $65.76 on 30 October 2026 after a 28.58% fall. They are still about three times their August 2024 close but 53% below the June peak, because the rise rested on expectations of a turnaround that each weak forecast has put to the test.
August 2024: the collapse
On 1 August 2024, after the US close, Intel reported second-quarter revenue of $12.8 billion and a loss of $0.38 a share, and forecast third-quarter revenue of $12.5 to $13.5 billion, below the $14.39 billion analysts expected. It suspended its dividend from the fourth quarter and announced a $10 billion cost-reduction plan, including a cut of more than 15% of its workforce, about 15,000 jobs (Intel; Constellation Research; People Matters). The shares fell 26.06% on 2 August to $21.48 (Yahoo Finance), on a day when a weak US jobs report, 114,000 jobs added in July against 175,000 expected, pulled the whole market lower (CNN; Axios).
Late 2024 to mid-2025: the bottom
Chief executive Pat Gelsinger, whose main project had been to open Intel's factories to chips designed by other companies, the business model of Taiwan's TSMC, left on 1 December 2024 (PC Gamer; The Register). Two interim co-chief executives ran Intel until Lip-Bu Tan, the former head of the chip-design software company Cadence Design Systems, took over on 18 March 2025 (Neowin; WOSU). The shares rose 14.60% on 13 March, the day after his appointment was announced. They made their lowest close between August 2024 and October 2026, $18.13, on 8 April 2025, during the market fall that followed the US tariff announcement of 2 April, and rose 18.75% the next day when the US paused most of the higher tariffs for 90 days (NPR; Yahoo Finance).
August 2025 to January 2026: outside money
In August 2025 SoftBank agreed to buy $2 billion of Intel shares at $23 each, and days later the US government took a stake of about 9.9%: 433.3 million shares at $20.47 each, for $8.9 billion. The money came from $5.7 billion of grants Intel had been awarded but not yet paid under the CHIPS Act, the 2022 law that subsidises chip factories in the US, and $3.2 billion from the Secure Enclave program, a separate government chip programme (CBS News; Tom's Hardware). On 18 September 2025 Nvidia agreed to buy $5 billion of Intel shares at $23.28 each and to develop chips with Intel for data centres and PCs; Intel's shares rose 22.77% that day to $30.57 (Yahoo Finance; MarketBeat). The shares ended 2025 at $36.90 and reached $54.32 on 22 January 2026, then fell 17.03% the next day when Intel forecast first-quarter revenue of $11.7 to $12.7 billion, below expectations, and said it could not make enough of its server chips to meet demand (Motley Fool; Nasdaq).
April to June 2026: AI demand lifts the shares
Demand for Intel's processors, the general-purpose chips that run alongside AI chips in data centres, then became the main reason investors gave for buying the shares. First-quarter results published on 23 April beat forecasts, with revenue of $13.6 billion and data-centre and AI revenue up 22% from a year earlier, and the shares rose 23.60% on 24 April to $82.54 (24 Apr briefing). Bank of America raised its rating on 11 June, citing booming orders for processors for AI data centres, and the shares rose 9.27%; on 18 June President Trump announced that Intel would design and build chips in the US with Apple, and they rose 10.64% (11 Jun and 18 Jun briefings). The shares made their highest close on 22 June, $140.94, more than seven times the April 2025 low (Yahoo Finance).
July to October 2026: from the peak to the 30 October fall
The shares lost 35% in July, closing the month at $90.20, as chip makers sold off; second-quarter results that beat forecasts (27 Jul briefing) did not stop the fall. They recovered to $127.39 on 24 September, helped by reported price increases (up 9.05% on 8 September) and a Micro LED packaging partnership with Taiwan's AUO (up 12.14% on 21 September) (8 Sep and 21 Sep briefings), then lost 29.5% by 16 October (Yahoo Finance). On 29 October Intel reported third-quarter revenue up 21% at $16.5 billion but forecast $15 to $16 billion for the fourth quarter, below the roughly $17 billion analysts expected, and the shares fell 28.58% on 30 October to $65.76 (29 Oct briefing; Yahoo Finance). The government's 433.3 million shares were worth about $28.5 billion at that close, about $11.4 billion less than the day before but still more than three times their cost.
What the moves show
| Date | Close ($) | Day's change | Event |
|---|---|---|---|
| 2 Aug 2024 | 21.48 | −26.06% | Weak results, dividend suspended, job cuts |
| 8 Apr 2025 | 18.13 | Lowest close, after the US tariff announcement | |
| 18 Sep 2025 | 30.57 | +22.77% | Nvidia's $5 billion investment |
| 23 Jan 2026 | 45.07 | −17.03% | Weak first-quarter forecast, supply shortage |
| 24 Apr 2026 | 82.54 | +23.60% | First-quarter results beat forecasts |
| 22 Jun 2026 | 140.94 | Highest close | |
| 24 Sep 2026 | 127.39 | September high | |
| 30 Oct 2026 | 65.76 | −28.58% | Weak fourth-quarter forecast |
Source: Yahoo Finance daily closes.
Of the five largest daily moves between 1 August 2024 and 30 October 2026, three came the day after quarterly results: the falls of 28.58% on 30 October 2026 and 26.06% on 2 August 2024, and the 23.60% rise on 24 April 2026. The other two were Nvidia's investment (+22.77%) and the tariff pause (+18.75%) (Yahoo Finance). From the April 2025 low, the price rose on the expectation that outside money and AI demand would turn Intel around, so each quarterly forecast became a test of that expectation: when the forecast fell short, as on 23 January and 30 October 2026, the shares lost between a sixth and more than a quarter of their value in a day.
Data sources: US Treasury par and real curves (30 Oct 2026) and FRED (policy rates, VIX, credit spreads, macro); ECB YC API (AAA curve, 29 Oct 2026) and ECB SPF (2026 Q4); equity indices, ETF P/E proxies, commodity futures, US sector funds, individual stock prices, the Philadelphia semiconductor index, the Russell 2000 and the VIX at the 30 Oct close, and FX quoted at 18:58–19:08 CET, via Yahoo Finance; European, UK and Japanese bond yields, economic releases and news via web search (Trading Economics, CNBC, FinanceFeeds, Newsquawk, People's Daily, China-Global South Project).