2026 10 12
Global Financial Briefing — Monday, 12 October 2026
Figures reflect the 12 Oct close wherever close data exists. FX quotes and the French, UK, Japanese and Italian bond yields are evening quotes; other figures are dated inline.
Market Overview
The largest move of the day was in South Korea, where the Kospi fell 3.65% to 6,384.24 in its first session since 8 October (Friday was Hangul Day). Foreign investors sold about 2 trillion won of Korean shares and analysts tied the fall to the end of Samsung Electronics' share buyback (SBS News); Samsung and SK Hynix, which together make up more than half of the index, lost about 4.5% each, and the Kosdaq fell 4.8% (ZeroHedge). Memory-chip makers were also hit by China's CXMT, whose president said the company had made key progress on a denser memory-cell design (called 4F², against the 6F² cell used in mainstream DRAM today) and plans a server-memory product on it by the end of 2026 (ZeroHedge). The selling reached New York: Micron closed down 3.9% at $989.04 and Sandisk down 6.0% (Yahoo Finance), the US technology sector fund (XLK) fell 1.22% and the Nasdaq 100 0.71%, while the Dow rose 0.38% and the S&P 500 was little changed (−0.06%). The Kospi has lost 8.85% since its 2 October close and is 31.98% below its 52-week high of 9,385.59, holding just 0.31% above its 200-day average.
Oil rose for a third session in a row, after the December Brent contract settled at $100.20 on 7 October. The December Brent contract (BZZ26) settled at $106.65 a barrel, 1.84% above Friday's settlement, after Yemen's Houthi movement struck Riyadh's main airport over the weekend, killing at least 12 people (Yahoo Finance; OilPrice.com reports 13 dead and more than 300 wounded), and two tankers were hit, one near Oman and one in the Strait of Hormuz (OilPrice.com). President Trump suggested the US could join Saudi strikes on the Houthis (Yahoo Finance). His announcement on Sunday that Russia and Ukraine had agreed to stop attacking each other's energy infrastructure did little to calm the market: on Monday President Zelensky accused Russia of breaking it, and Moscow declined to confirm that any agreement existed (OilPrice.com, FXStreet). Goldman Sachs raised its forecast for Brent in December to $90 a barrel from $85, about $17 below Monday's settlement: the bank estimates that the risk of supply disruption accounts for just over $20 of today's price, so its forecast implies that most of that premium fades by the end of the year (OilPrice.com).
Europe rose despite oil, led by banks: the STOXX 600 gained 0.65%, the FTSE 100 0.99%, the DAX 0.76%, the SMI 0.66% and the CAC 40 0.38%. The US cash Treasury market was closed for Columbus Day (SIFMA, via ZeroHedge), so there was no new Treasury close and the 10-year yield stands at Friday's 5.24%. In Europe the German 10-year yield eased 1 bp to 3.47% while France's rose 4 bp to 4.91%, close to its more than two-decade high of 5.03%, on the eve of the National Assembly's debate on the 2027 budget, which aims to cut the deficit to 5% of GDP (Trading Economics, Il Sole 24 Ore). The extra yield France pays over Germany for ten-year money widened to 143 bp from 139 bp on Friday's quotes. The euro fell 0.41% to $1.1159, near its lowest in about 17 months, as traders weighed French debt and a firm dollar (FXStreet). In Asia, Hong Kong's Hang Seng rose 0.25% on banks and insurers while mainland shares fell, the Shanghai Composite by 0.43% and the Shenzhen Component by 2.03% (RTHK, The Standard). Japan was closed for Sports Day.
Global Indices Snapshot
Americas
| Index | Level | Day Chg | Day Chg % | Source |
|---|---|---|---|---|
| S&P 500 | 7,807.24 | −4.30 | −0.06% | yfinance ^GSPC |
| Nasdaq 100 | 30,664.70 | −218.45 | −0.71% | yfinance ^NDX |
| Dow Jones | 51,850.60 | +195.70 | +0.38% | yfinance ^DJI |
| Brazil IBOV | 209,066.90 † | — | — | yfinance ^BVSP |
Americas data reflects the 12 Oct close.
† Brazil IBOV: 12 Oct 2026 is Our Lady of Aparecida, market closed today; the level is the 9 Oct close.
The S&P 500 is 0.48% below its record of 7,844.52, 1.35% above its 50-day average and 7.61% above its 200-day average. The Nasdaq 100 is 2.22% below its 52-week high and 2.82% above its 50-day average. The Dow is 1.46% below its 50-day average and 5.29% below its 52-week high of 54,744.33. Brazil's Ibovespa closed Friday 0.31% below its 52-week high, ahead of the 25 October presidential runoff.
Europe
| Index | Level | Day Chg | Day Chg % | Source |
|---|---|---|---|---|
| Euro STOXX 600 | 635.65 | +4.10 | +0.65% | yfinance ^STOXX |
| CAC 40 | 7,832.88 | +29.55 | +0.38% | yfinance ^FCHI |
| DAX | 25,277.68 | +190.41 | +0.76% | yfinance ^GDAXI |
| FTSE 100 | 10,656.28 | +104.23 | +0.99% | yfinance ^FTSE |
| SMI (Swiss) | 13,877.84 | +90.44 | +0.66% | yfinance ^SSMI |
European data reflects today's close (12 Oct).
The Euro STOXX 50, which holds only the largest euro-area companies, rose 0.45% to 6,201.21. Banks led early, the STOXX 600 bank sector up about 1.5% by mid-morning (Reuters), and Milan's main index returned to 50,000 points on its banks (Il Sole 24 Ore). In Paris, Hermès rose 2.1% and Société Générale 1.8%, and the market held its gains despite higher oil and the pressure on French bonds (Abcbourse); investors were waiting for the company results season, which starts this week (Boursorama). The CAC 40 remains the weakest of the major European indices: 5.38% below its 50-day average, 4.83% below its 200-day average and only 4.37% above the bottom of its 52-week range (7,505.27 to 8,755.03). The STOXX 600 is 1.57% below its 50-day average and 1.67% above its 200-day average; the DAX is 1.69% above its 200-day average.
Asia-Pacific
| Index | Level | Day Chg | Day Chg % | Source |
|---|---|---|---|---|
| Nikkei 225 | 69,030.92 † | — | — | yfinance ^N225 |
| Hang Seng | 24,271.20 | +59.85 | +0.25% | yfinance ^HSI |
| Shanghai Comp | 3,797.24 | −16.55 | −0.43% | yfinance 000001.SS |
| ASX 200 | 8,783.20 | +66.60 | +0.76% | yfinance ^AXJO |
| Kospi (Korea) | 6,384.24 | −241.69 | −3.65% | yfinance ^KS11 |
Asia-Pacific data reflects today's close (12 Oct).
† Nikkei 225: 12 Oct 2026 is Sports Day, market closed today; the level is the 9 Oct close.
The Kospi's change is against its 8 Oct close, the last session before the Hangul Day holiday, so it covers two days of news elsewhere.
The Kospi's fall was broad: the KRX semiconductor index lost 5.2% (ZeroHedge), and foreign investors were the main sellers, institutions selling a further 110 billion won (SBS News). In China, the Shenzhen Component fell 2.03% to 12,384.87 and the ChiNext board of growth companies about 2.6%; brokers cited rising global bond yields and US investigations of the electronics manufacturers Luxshare and Foxconn Industrial Internet (RTHK, The Standard). The Shanghai Composite is now only 1.50% above its 52-week low of 3,741.11. In Hong Kong, banks and insurers rose while the Hang Seng Tech index fell about 0.7% on chip and AI stocks (The Standard). Australia's ASX 200 gained 0.76%.
Emerging Markets
| Index | Level | Day Chg % | Source |
|---|---|---|---|
| MSCI EM (EEM) | 66.15 | −0.97% | yfinance EEM |
| India Nifty 50 | 22,363.35 | −0.70% | yfinance ^NSEI |
| South Africa | 63.77 | −0.05% | yfinance EZA |
All three are 12 Oct closes, MSCI EM (EEM) and South Africa (EZA) in New York.
EEM's 0.97% fall in New York follows the Asian markets that closed before New York opened, led by Korea (−3.65%), with mainland China (−0.43%) and India (−0.70%) also lower and Hong Kong (+0.25%) the exception; so the New York price and the local closes point the same way. India's Nifty opened higher and reversed on continued selling by foreign institutions and higher bond yields (Mint, via inkl); it is 0.83% above its 52-week low of 22,179.90 and 5.75% below its 50-day average. The South Africa fund was little changed.
Index Valuations & Investment Risk
Valuation Table
| Index | Trailing P/E (live) | 50-day avg | 100-day avg | 200-day avg |
|---|---|---|---|---|
| S&P 500 | 25.1x | 25.4x | 26.2x | — |
| Nasdaq 100 | 30.4x | 30.3x | 31.6x | — |
| Euro STOXX 600 | 17.6x | 17.9x | 18.2x | — |
| CAC 40 | 16.5x | 17.0x | 17.3x | — |
| DAX | 17.9x | 18.5x | 18.5x | — |
| FTSE 100 | 16.5x | 16.9x | 17.4x | — |
| Nikkei 225 | 18.1x | — | — | — |
| MSCI EM | 14.1x | 15.7x | 16.6x | — |
Averages of the daily trailing P/E readings recorded since 1 May 2026 (n = 108); shown for reference only.
Nikkei 225 (1321.T): the reading is the 9 Oct close, Tokyo being shut today; its averages are withheld because they include four days of 0.23x readings that were data errors (n = 107).
Investment Risk Assessment for ETF Investors
United States (S&P 500 / Nasdaq ETFs)
The S&P 500's trailing P/E of 25.1x gives an earnings yield of 3.98% (1÷25.14). Against the 10-year Treasury at 5.24% (US Treasury par curve, 9 Oct; no Treasury session today) the earnings yield gap is −1.26 pp: a 10-year government bond pays more in income than the index's earnings come to per dollar invested. Against the real 10-year yield of 2.91% (US Treasury real curve, 9 Oct) the gap is +1.07 pp; the 2.33 pp between the two is the correction for company earnings growing with inflation while a bond coupon is fixed. Only the part of earnings paid out as dividends and buybacks reaches a holder as cash. The Nasdaq 100 at 30.4x has an earnings yield of 3.29%, 1.95 pp below the 10-year Treasury. Today showed how concentrated that index's risk is in a few chip and AI companies: a Chinese company's progress on memory-chip design was enough to take Micron down 3.9% and the technology sector fund down 1.22%, while the Dow rose 0.38%. Analysts expect third-quarter profits of S&P 500 companies to be about 25% higher than a year earlier, and Goldman Sachs strategists moved global equities to overweight for the short term (Yahoo Finance); the results season starts tomorrow with the large US banks, whose shares have fallen 7% to 13% over the past month (Bank of America −13%, Goldman Sachs −12%, Morgan Stanley −11%, Wells Fargo −7%; Yahoo Finance).
Europe (STOXX 600 / CAC 40 / DAX ETFs)
The STOXX 600 at 17.6x gives an earnings yield of 5.69% (1÷17.56); against the euro AAA 10-year yield of 3.51% (ECB YC API, 9 Oct) the euro earnings yield gap is +2.18 pp, and against today's 10-year Bund quote of 3.47% (Trading Economics) it is +2.22 pp. Against the euro-area real 10-year yield of 1.47% (see Real Yields below) it is +4.22 pp. The S&P 500 trades at a 43.1% P/E premium to the STOXX 600 (25.1x against 17.6x). Part of the difference between the US and euro gaps reflects different inflation and policy paths rather than different compensation for risk, which is why the real-yield versions are shown alongside. The CAC 40 at 16.5x has an earnings yield of 6.07% (1÷16.47), only 1.17 pp above the French 10-year yield of 4.91%, a thin margin because French government bonds now pay so much. The DAX at 17.9x yields 5.58%, 2.11 pp above the Bund, and the FTSE 100 at 16.5x yields 6.06%, 0.61 pp above the 10-year gilt at 5.45%. For a French investor the near-term risk is domestic: the National Assembly starts debating the 2027 budget tomorrow without a stable majority behind the government, and if no budget passes France would fall back on an emergency financing law, as in 2025 and 2026 (Il Sole 24 Ore, ING). A euro investor in euro-quoted funds has no exchange-rate effect on the quoted value, but the constituents earn much of their profit abroad, so the euro's level against the dollar still feeds into their earnings.
Japan (Nikkei / TOPIX ETFs)
Tokyo was closed, so the Nikkei proxy's 18.1x (earnings yield 5.54%) is Friday's reading; it came back on 9 October after four days of erroneous figures and is still about 21% below the 22.7x of 2 October at a similar index level, so treat it with caution until it holds for several days. The Bank of Japan raised its policy rate to 1.25% on 18 September, by a 7–2 vote, from the 1.00% set in June (Free Press Journal); its next meeting is on 29–30 October. The yen fell 0.28% against the dollar to 158.69 but gained about 0.1% against the euro, which fell further, so an unhedged Japan fund gained slightly on the currency for a euro investor today.
Emerging Markets (MSCI EM ETFs)
EEM trades at 14.1x, the cheapest of the indices in the table and a 44.0% discount to the S&P 500. Today showed the main concentration inside it: Korea's two largest companies are memory-chip makers, and their 4.5% falls took the Kospi down 3.65%. The dollar rose 0.35% against the six currencies in the ICE index. A stronger dollar makes dollar debts dearer for emerging-market borrowers and tends to draw money out of their markets; for a euro holder the conversion effect is partly offset because the euro fell against the dollar too (−0.41%), but the economic effect on local share prices applies whatever the investor's currency. Oil above $100 adds to the pressure on importers such as India and Korea.
Overall Risk Score: - United States: High valuation risk / low margin of safety. A negative nominal earnings yield gap, a 10-year yield of 5.24%, a September CPI due on Wednesday and an index whose largest companies move together on news about AI and chips. - Europe: Moderate. Positive earnings yield gaps on both measures and a P/E well below the US; against that, oil above $100, the French budget debate starting tomorrow and the CAC 40 below both its 50- and 200-day averages. - Japan: Moderate. A P/E reading that has only just come back and needs confirming; BOJ rate rises and the yen near 159 per dollar are the main risks. - Emerging Markets: Attractive relative valuation, with Korea's chipmakers, oil, the dollar and Brazil's 25 October runoff as the near-term risks.
US Economic Indicators (FRED - authoritative)
| Indicator | Current | Prior | Delta | Reference Date | FRED Series |
|---|---|---|---|---|---|
| CPI YoY % | 3.35% | 3.30% | +0.05 pp | Aug 2026 (prior Jul) | CPIAUCSL |
| Core CPI YoY % | 2.45% | 2.47% | −0.02 pp | Aug 2026 (prior Jul) | CPILFESL |
| Unemployment Rate | 4.2% | 4.1% | +0.10 pp | Sep 2026 (prior Aug) | UNRATE |
| Nonfarm Payrolls | +29k | +133k | −104k | Sep 2026 (prior Aug), monthly chg | PAYEMS |
| 10Y TIPS Real Yield | 2.91% | 2.87% | +4 bp | 9 Oct 2026 (prior 8 Oct) | DFII10 (US Treasury real curve) |
The labour figures are the September release of 2 October; the CPI figures are August's. September's CPI is due on Wednesday 14 October, with forecasts of 3.6% for headline inflation over twelve months (+0.6% on the month) and 2.5% for core inflation (+0.2%) (ZeroHedge). The real yield is unchanged since Friday's briefing, as there was no Treasury session today.
Other economic releases today: none of note. US markets had no scheduled data, and the bond market was closed for Columbus Day (ZeroHedge). The IMF and World Bank annual meetings opened in Bangkok and run until 18 October.
Fixed Income & Bond Analysis
Policy Rates
| Central Bank | Rate | Source |
|---|---|---|
| Fed Funds (upper) | 4.00% | FRED DFEDTARU (12 Oct 2026) |
| Fed Funds (lower) | 3.75% | FRED DFEDTARL (12 Oct 2026) |
| Effective FFR | 3.88% | FRED DFF (8 Oct 2026) |
| ECB Deposit Rate | 2.50% | FRED ECBDFR (12 Oct 2026) |
| BOJ Policy Rate | 1.25% | web search (raised 18 Sep 2026) |
| BOE Bank Rate | ~3.73% (SONIA/FRED) | FRED IUDSOIA (8 Oct 2026) |
Markets price four Bank of England rate rises over the next twelve months from today's 3.75% (Trading Economics). On 9 October they priced the ECB deposit rate at 2.72% by December, most of one further 25 bp rise from 2.50% (Trading Economics). The Fed raised its target range by 25 bp to 3.75–4.00% at its 15–16 September meeting and next meets on 27–28 October.
Government Bond Yields
| Country | 2Y Yield | 10Y Yield | 30Y Yield | Day Chg (10Y) | Source |
|---|---|---|---|---|---|
| USA | 4.80% | 5.24% | 5.60% | +2 bp | US Treasury par curve (9 Oct 2026) |
| Euro area AAA (ECB) | 3.05% | 3.51% | 3.78% | −1 bp | ECB YC API (9 Oct 2026) |
| Germany | 3.12% | 3.47% | 3.84% | −1 bp | web (Trading Economics, 12 Oct 2026) |
| France | — | 4.91% | — | +4 bp | web (Trading Economics, 12 Oct 2026) |
| UK | 4.77% | 5.45% | — | +2 bp | web (Trading Economics, 12 Oct 2026) |
| Japan | — | 3.02% † | — | — | web (Trading Economics, 9 Oct 2026) |
| Italy | — | 4.58% | — | +1 bp | web (Trading Economics, 12 Oct 2026) |
The USA row is the 9 Oct curve, with its day change against 8 Oct 2026: the US bond market was closed today for Columbus Day, so no newer curve exists. The Euro area AAA row's day change is against the 8 Oct 2026 curve. The other rows are 12 Oct quotes, with day changes as Trading Economics reports them.
† Japan: market closed for Sports Day; the level is the 9 Oct close.
Yield Curve Spreads (US Treasury par curve, 9 Oct 2026): - 10Y-2Y spread: +44 bp, positive, 19 bp outside the ±25 bp flat band and under the 75 bp steep threshold. - 10Y-3M spread: +99 bp, positive, no recession signal.
OAT-Bund Spread: 143 bp (10-year OAT 4.91% against Bund 3.47%, Trading Economics, 12 Oct 2026), against 139 bp on Friday's quotes from the same source.
Positive US spreads of this size are what investors normally demand for lending for longer; they do not signal an expected recession. In the euro area France moved away from Germany today: its 10-year yield rose 4 bp while the Bund's eased 1 bp, so the spread widened by 4 bp in a single session ahead of the budget debate, after narrowing on Friday. Italy's spread over Germany was little changed at about 111 bp, with the 10-year BTP at 4.58% (Trading Economics), so the French move was specific to France rather than a general sale of euro-area government bonds. Italy now borrows for ten years about a third of a point more cheaply than France. The 10-year gilt rose 2 bp to 5.45%, still the highest 10-year yield in the table, and the 2-year gilt 3 bp to 4.77%; markets price four Bank of England rises over the coming year (Trading Economics).
Yield Curve Charts
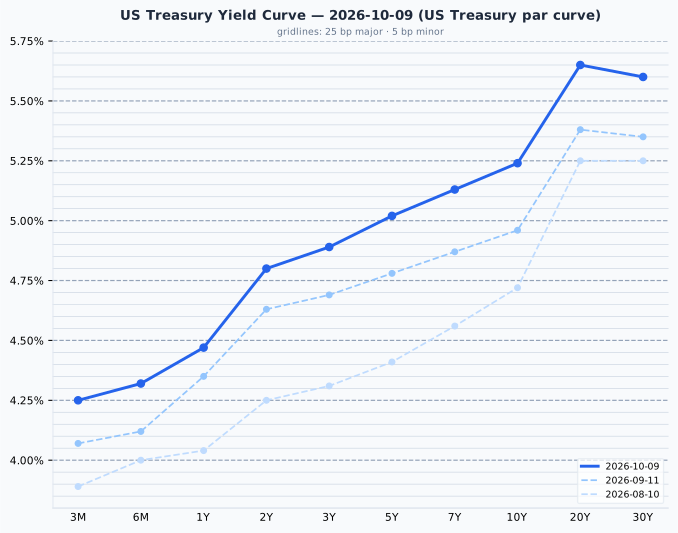
US Treasury par curve, 9 Oct 2026 (the latest: no Treasury session on 12 Oct): 3M 4.25%, 6M 4.32%, 1Y 4.47%, 2Y 4.80%, 3Y 4.89%, 5Y 5.02%, 7Y 5.13%, 10Y 5.24%, 20Y 5.65%, 30Y 5.60%; 2-to-10 slope +44 bp. Prior curves: 11 Sep and 10 Aug 2026. The 3-month bill at 4.25% is 37.5 bp above the Fed Funds midpoint of 3.875%, more than the usual 25 bp, consistent with markets still allowing for a further rate rise by December.
The US curve rises from 4.25% at three months to 5.65% at 20 years, with the 30-year 5 bp below the 20-year. Since 11 September every maturity is higher, most at seven to twenty years (+26 to +28 bp) and least at one year (+12 bp), so the curve has steepened over the month.
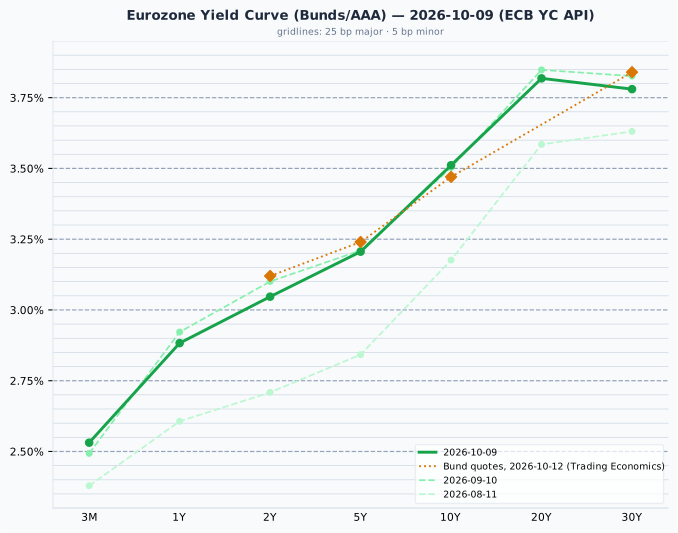
Euro area AAA government curve, 9 Oct 2026 (ECB YC API): 3M 2.53%, 1Y 2.88%, 2Y 3.05%, 5Y 3.21%, 10Y 3.51%, 20Y 3.82%, 30Y 3.78%; 2-to-10 slope +46 bp. Prior curves: 10 Sep and 11 Aug 2026. Today's Bund quotes (Trading Economics, 12 Oct 2026), shown as amber markers, differ from the plotted 9 Oct curve by at most 7 bp, at the 2-year (3.12% against 3.05%), by 6 bp at the 30-year (3.84% against 3.78%) and by 4 bp at the 10-year (3.47% against 3.51%). The curve is the ECB's fitted AAA euro-area composite and the quotes are on-the-run German bonds, which sit a few basis points apart by construction, so these gaps are mostly the difference between the two measures rather than a day move.
The euro AAA curve rises from 2.53% at three months to 3.82% at 20 years, with the 30-year 4 bp below the 20-year. On 9 October it barely moved (the 2-year +1 bp, the 10-year −1 bp), and against 10 September every maturity is within 5 bp of where it was, while US yields from five to thirty years rose 24 to 28 bp over the same month.
Credit Markets (from FRED - authoritative)
| Market | OAS | Obs. date | vs prior obs | Series ID |
|---|---|---|---|---|
| US Investment Grade | 82 bp | 8 Oct 2026 | 0 bp | BAMLC0A0CM |
| US High Yield | 315 bp | 8 Oct 2026 | +6 bp | BAMLH0A0HYM2 |
| Euro High Yield | 326 bp | 8 Oct 2026 | +4 bp | BAMLHE00EHYIOAS |
Change is 8 Oct 2026 vs 7 Oct 2026. Credit spreads are the 8 October close; today's session is not in them yet, and FRED had not yet published the 9 October readings.
US high-yield spreads, the extra yield on lower-rated company bonds over Treasuries, are at 315 bp, in the lower half of their normal 300–500 bp range; investment-grade spreads at 82 bp are at the bottom of their 80–150 bp range. Euro high-yield spreads are 326 bp. The VIX closed at 14.84 on 9 October (FRED VIXCLS), a low reading, and closed at 15.21 on 12 October (Yahoo Finance).
Real Yields (US and Euro Area)
| Region | Nominal 10Y | Expected inflation | Real 10Y | How the real yield is obtained |
|---|---|---|---|---|
| United States | 5.24% (US Treasury par curve, 9 Oct 2026) | 2.33% (residual: nominal − real) | 2.91% (US Treasury real curve, 9 Oct 2026) | Measured. TIPS trade, so the market quotes a real yield directly; expected inflation is the residual (the breakeven) |
| Euro area | 3.51% (ECB YC API, 9 Oct 2026) | 2.04% (ECB SPF, 2026 Q3, measured) | 1.47% (residual: nominal − expected) | Constructed. No euro inflation-linked benchmark is published, so a survey expectation is subtracted from the nominal yield |
Only the US real yield is a market price; the euro figure is derived from a survey and is the softer of the two. Two mismatches apply when comparing them: the US breakeven includes a premium investors demand for inflation risk, which a survey does not, and the survey looks five years ahead against the bond's ten. Both legs are dated 9 October. The 173 bp gap between US and euro nominal 10-year yields splits into 29 bp of expected-inflation difference (2.33% against 2.04%) and 144 bp of real-rate difference (2.91% against 1.47%), so the gap is almost entirely real. The US real yield's last change was +4 bp on 9 October (against 2.87% on 8 October).
Why the US real-yield advantage is not a return a euro investor can capture
The US real yield has exceeded the euro one in every quarter since 2014, by 1.52 pp on average, and the 144 bp of 9 October is a little below that mean. It is a structural feature (US trend growth, euro-area savings, the scarcity of German government bonds, heavy US government borrowing), not a return a euro-based reader can capture: hedging the currency removes it, because the forward exchange rate is set from the same interest differential, and holding Treasuries unhedged is a bet on the dollar rather than a bond decision. A real yield is real in its own currency; a US real yield of 2.91% is that much above US inflation, which is not a real return for someone who spends euros. The gap is stated here as a description of relative policy stance and growth expectations, and no portfolio conclusion is drawn from it.
Bond Portfolio Implications
A 10 bp rise in yields is an ordinary day's move. At the 9 Oct 2026 par yields it costs:
| Maturity | Yield | Modified duration | Loss for a 10 bp rise | Months of coupon lost |
|---|---|---|---|---|
| 2-year | 4.80% | 1.89 | 0.19% | 0.5 |
| 10-year | 5.24% | 7.71 | 0.77% | 1.8 |
| 30-year | 5.60% | 14.45 | 1.43% | 3.1 |
Months of coupon lost is the loss divided by one month of coupon (yield ÷ 12) on a par bond. Source: US Treasury par curve, 9 October.
The 30-year pays 0.80 pp more than the 2-year for more than seven times as much loss per 10 bp. With the September CPI due on Wednesday, forecast to show inflation rising to 3.6%, and a Fed that raised rates in September, short maturities keep most of the income for far less exposure. For euro bonds the same arithmetic applies to France: at 4.91% the French 10-year pays 1.43 pp more than the Bund, and today's 4 bp widening shows how quickly that extra income can be lost in price.
Currencies & Commodities
Currencies (Yahoo Finance live quotes)
| Pair | Rate | Day chg % | Source |
|---|---|---|---|
| EUR/USD | 1.1159 | −0.41% | yfinance (18:54 CEST) |
| USD Index (DXY, ICE) | 102.57 | +0.35% | yfinance (18:45 CEST) |
| USD/JPY | 158.69 | +0.28% | yfinance (18:55 CEST) |
| GBP/USD | 1.3204 | −0.22% | yfinance (18:54 CEST) |
| USD/CHF | 0.8347 | +0.57% | yfinance (18:55 CEST) |
FX quotes as of 18:55 CEST; day change vs the previous 17:00 ET close.
The dollar rose 0.35% against the six currencies in the ICE index and gained against every currency in the table. The euro fell 0.41% to $1.1159, near a 17-month low, with the dollar's broad rise (FXStreet also cites French debt concerns); it has lost more than 3% in five weeks (BeInCrypto). The Swiss franc fell 0.57% against the dollar to 0.8347 per dollar even with conflict in the Gulf, and slightly against the euro too, so it did not act as a refuge today. The yen weakened 0.28% to 158.69 per dollar and the pound 0.22% to $1.3204.
Commodities (Yahoo Finance front-month futures)
| Commodity | Price | Day Chg % | Ticker | Source |
|---|---|---|---|---|
| Brent Crude ($/bbl) | 106.65 | +1.84% | BZ=F | yfinance (BZZ26, Dec) |
| WTI Crude ($/bbl) | 93.74 | +2.06% | CL=F | yfinance (CLX26, Nov) |
| Gold ($/oz) | 4,190.60 | −0.61% | GC=F | yfinance (GCZ26, Dec) |
| Silver ($/oz) | 60.513 | −0.88% | SI=F | yfinance (SIZ26, Dec) |
| Copper ($/lb) | 6.747 | +0.82% | HG=F | yfinance (HGZ26, Dec) |
| Nat Gas ($/MMBtu) | 3.167 | −1.65% | NG=F | yfinance (NGX26, Nov) |
Prices are the 12 Oct 2026 settlements; day changes are settlement vs settlement (12 Oct vs 9 Oct 2026).
The December Brent contract (BZZ26) settled at $106.65, 1.84% above Friday's settlement of $104.72, and the November WTI contract (CLX26) at $93.74, up 2.06% from $91.85; by late morning Brent had reached its highest since 29 September (Sunday Guardian Live). The rise comes from the Gulf rather than the Gulf of Mexico: Shell, Chevron and BP were preparing to restore offshore output shut by Hurricane Isaias (OilPrice.com), while the tanker attacks threaten the recovery in Gulf oil exports, which reached 81% of their pre-war level in September (crude and condensate 91%, refined products 60%; OilPrice.com). Brent is 15.42% below its 52-week high of $126.10 (range $58.72 to $126.10) and WTI 21.54% below its high of $119.48 (range $54.98 to $119.48). The November WTI contract expires on 20 October.
Gold fell 0.61% to $4,190.60, 24.98% below its all-time high of $5,586.20 set on 29 January 2026, and silver fell 0.88% to $60.513, 50.11% below its all-time high of $121.30 set the same day. Copper rose 0.82% to $6.747, near its all-time high of $6.83 set on 22 September, 1.22% below it. Natural gas fell 1.65% to $3.167, in the lower part of its 52-week range of $2.483 to $7.827.
Sector & Theme Highlights
US sector funds (Select Sector SPDRs, 12 Oct close): eight of the eleven rose and three fell. Energy (XLE) +1.43% led with oil, followed by consumer staples (XLP) +1.17%, communication services (XLC) +0.97%, real estate (XLRE) +0.75%, health care (XLV) +0.69%, financials (XLF) +0.58%, utilities (XLU) +0.53% and materials (XLB) +0.02%. Technology (XLK) −1.22% fell most, with the memory-chip makers, followed by consumer discretionary (XLY) −0.51% and industrials (XLI) −0.06%. Chipotle fell 3.8% after Starbucks said it was not buying it (Yahoo Finance).
- Memory chips: the end of Samsung's share buyback and CXMT's progress on a denser DRAM design hit Samsung and SK Hynix in Seoul (about −4.5% each) and Micron (−3.9%) and Sandisk (−6.0%) in New York (ZeroHedge, SBS News, Yahoo Finance). CXMT's step matters because Samsung targets volume production of the same cell design only by 2028 (ZeroHedge).
- Oil and the Gulf: Houthi strikes on Saudi Arabia and attacks on tankers lifted December Brent to a $106.65 settlement, while the Russia–Ukraine energy truce announced by Trump on Sunday was disputed within a day.
- French public finances: the 10-year OAT at 4.91% and the euro near a 17-month low both reflect concern over France's budget, which parliament starts debating tomorrow.
- Bank earnings: US bank shares have fallen sharply over the past month, the KBW Nasdaq Bank index more than 14% below its August peak (Yahoo Finance), ahead of results from JPMorgan, Goldman Sachs, Citigroup and Wells Fargo on Tuesday.
Top Stories (Global)
- Kospi falls 3.65%. Korea's index dropped to 6,384.24 after the Hangul Day holiday as foreign investors sold about 2 trillion won, with Samsung and SK Hynix down about 4.5% each after Samsung's share buyback ended (SBS News, ZeroHedge).
- China's CXMT advances a denser memory chip. Its president reported key progress on a 4F² DRAM cell, with a server product planned by the end of 2026; Micron closed down 3.9%, below $1,000 (ZeroHedge, Yahoo Finance).
- Houthi strikes on Riyadh's airport lift oil. At least 12 people were killed over the weekend and two tankers were hit near Oman and in Hormuz; Brent settled 1.84% higher at $106.65, and Trump suggested the US could join Saudi strikes on the Houthis (OilPrice.com, Yahoo Finance).
- Russia–Ukraine energy truce disputed. Trump announced on Sunday that both sides would stop attacking energy infrastructure; on Monday Zelensky accused Russia of violating it and Moscow did not confirm a deal (OilPrice.com, FXStreet).
- French 10-year yield nears 5%. The OAT rose 4 bp to 4.91% before the National Assembly opens debate on a 2027 budget that targets a 5% deficit; the euro slipped to $1.1159 (Trading Economics, Il Sole 24 Ore, FXStreet).
- Mainland China shares fall. The Shenzhen Component lost 2.03%, which brokers put down to rising global yields and US investigations of Luxshare and Foxconn Industrial Internet, while the Hang Seng edged up 0.25% (RTHK, The Standard).
- Goldman raises its oil forecast and its equity call. Brent in December to $90 a barrel from $85, still about $17 below Monday's settlement, and global stocks to overweight for the short term (OilPrice.com, Yahoo Finance).
Looking Ahead
- Tuesday 13 October: JPMorgan, Goldman Sachs, Citigroup, Wells Fargo, Johnson & Johnson and UnitedHealth report third-quarter results; the IMF publishes its World Economic Outlook; Fed Governor Waller speaks on AI and economic policy; Japan's September producer prices; France's National Assembly begins debating the 2027 budget (ZeroHedge, Il Sole 24 Ore).
- Wednesday 14 October: US September CPI, forecast at 3.6% over twelve months (core 2.5%); the Fed's Beige Book survey of regional business conditions; China's September consumer and producer prices and trade; ASML, Bank of America, Morgan Stanley and BlackRock report (ZeroHedge).
- Thursday 15 October: US retail sales and producer prices, UK August GDP, TSMC results; Fed Chair Kevin Warsh in conversation with IMF Managing Director Kristalina Georgieva in Bangkok, possibly his last public remarks before the Fed's pre-meeting quiet period (ZeroHedge's calendar also lists him on Friday); European Council meets on 15–16 October; G20 finance ministers and central bank governors meet (ZeroHedge).
- Friday 16 October: US industrial production and import prices (ZeroHedge).
- Later this month: Brazil's presidential runoff on 25 October; the Fed meets on 27–28 October and the Bank of Japan on 29–30 October. US midterm elections on 3 November.
Market closures - None in the next five days. - No Indian holiday data is available here, so Indian closures are not checked.
Data sources: US Treasury par and real curves (9 Oct 2026; no Treasury session on 12 Oct) and FRED (policy rates, VIX, credit spreads, macro); ECB YC API (AAA curve, 9 Oct 2026) and ECB SPF (2026 Q3); equity indices, ETF P/E proxies, commodity settlements and sector funds via Yahoo Finance (12 Oct closes), FX via Yahoo Finance (as of 18:55 CEST); European, UK and Japanese bond yields, economic calendar and news via web search (Trading Economics, ANSA, Il Sole 24 Ore, SBS News, ZeroHedge, Yahoo Finance, OilPrice.com, Sunday Guardian Live, FXStreet, BeInCrypto, RTHK, The Standard, Mint via inkl, Abcbourse, Boursorama, ING, Free Press Journal).