2026 07 21
Global Financial Briefing — Tuesday, 21 July 2026
Market Overview
Global equities are broadly risk-on Tuesday, led by a powerful Asia-Pacific rally and a firm U.S. session, but the tape is trading ahead of the day's dominant catalyst: the FOMC is scheduled to announce its policy decision at 2:00pm ET, with the Fed Funds target range currently sitting at 3.50–3.75% (FRED DFEDTARL/DFEDTARU, unchanged through 2026-07-21). Nothing in the futures-implied path has shifted yet, but positioning into the decision explains some of the day's caution alongside the gains.
Asia-Pacific is the standout: Japan's Nikkei 225 surged +3.26% (FRED/yfinance ^N225) as the market reopened after Monday's Marine Day holiday, and Korea's Kospi jumped +3.56%, both driven by chip-sector strength (Samsung Electronics, TSMC) per market wires — consistent with the MSCI Asia Pacific Index's reported +1.7% move. Europe is firmer but more measured (STOXX 600 +0.56%), helped by a Novartis earnings beat, while the U.S. session (still in progress at data-pull time, ^GSPC +0.87%, ^NDX +1.93%, ^DJI +0.85%) is running broadly in line with the global tone. A notable cross-current: gold and silver are both deeply off their 52-week/all-time highs — gold 27% below its $5,586.20 ATH, silver 51% below its $121.30 ATH — even as copper trades within 2% of its own record, underscoring a highly uneven commodity complex.
Fixed income is quiet ahead of the Fed: the 10Y Treasury sits at 4.55% (FRED DGS10, 2026-07-17), the curve is positively sloped but not steep (10Y-2Y spread +39bps, FRED T10Y2Y), and credit spreads remain historically tight (US HY OAS 269bps, US IG OAS 78bps) — a signal of continued risk-on complacency rather than stress. The VIX sits at 18.65 (FRED VIXCLS, 2026-07-20) — moderate rather than low, suggesting some hedging demand persists into the Fed decision. JPMorgan CEO Jamie Dimon's public caution on both equities and long-dated Treasurys, citing geopolitical tension and fiscal deficits, is a useful counterweight to the day's exuberance.
Global Indices Snapshot
Note: U.S. figures below are from the open session on 21 July, not the final close.
Americas
| Index | Level | Day Chg | Day Chg % | Source |
|---|---|---|---|---|
| S&P 500 | 7,508.38 | +65.10 | +0.87% | yfinance ^GSPC |
| Nasdaq 100 | 29,156.01 | +551.77 | +1.93% | yfinance ^NDX |
| Dow Jones | 52,280.81 | +441.55 | +0.85% | yfinance ^DJI |
| Brazil IBOV | 173,052.39 | -318.95 | -0.18% | yfinance ^BVSP |
Europe
| Index | Level | Day Chg | Day Chg % | Source |
|---|---|---|---|---|
| Euro STOXX 600 | 643.19 | +3.59 | +0.56% | yfinance ^STOXX |
| Euro STOXX 50 | 6,285.63 | +58.23 | +0.94% | yfinance ^STOXX50E |
| CAC 40 | 8,363.14 | +23.03 | +0.28% | yfinance ^FCHI |
| DAX | 25,011.35 | +164.66 | +0.66% | yfinance ^GDAXI |
| FTSE 100 | 10,585.91 | +61.15 | +0.58% | yfinance ^FTSE |
| SMI (Swiss) | 14,298.26 | +43.90 | +0.31% | yfinance ^SSMI |
European data reflects today's close (21 Jul).
Asia-Pacific
| Index | Level | Day Chg | Day Chg % | Source |
|---|---|---|---|---|
| Nikkei 225 | 66,232.19 | +2,091.07 | +3.26% | yfinance ^N225 |
| Hang Seng | 25,132.29 | -10.76 | -0.04% | yfinance ^HSI |
| Shanghai Comp | 3,864.37 | +68.09 | +1.79% | yfinance 000001.SS |
| ASX 200 | 8,793.30 | +2.00 | +0.02% | yfinance ^AXJO |
| Kospi (Korea) | 6,747.95 | +231.68 | +3.56% | yfinance ^KS11 |
Asia-Pacific data reflects today's close (21 Jul). Japan reopened today after Monday's Marine Day holiday (20 Jul), contributing to the Nikkei's outsized move.
Emerging Markets
| Index | Level | Day Chg % | Source |
|---|---|---|---|
| MSCI EM (EEM) | 65.41 | +2.91% | yfinance EEM |
| India Nifty 50 | 24,187.70 | -0.21% | yfinance ^NSEI |
| South Africa (EZA) | 62.34 | +1.14% | yfinance EZA |
Index Valuations & Investment Risk
Valuation Table
| Index | Trailing P/E (live) | Hist avg trailing P/E (†) |
|---|---|---|
| S&P 500 | 26.92x | ~16-18x |
| Nasdaq 100 | 31.47x | ~25-30x |
| Euro STOXX 600 | 18.59x | ~15-17x |
| CAC 40 | 17.57x | ~14-16x |
| DAX | 18.29x | ~15-17x |
| FTSE 100 | 17.70x | ~13-15x |
| Nikkei 225 | 21.47x | ~20-22x |
| MSCI EM | 16.86x | ~13-15x |
(†) Hist avg trailing P/E: static long-run reference constants.
Trailing P/E (live): sourced from yfinance trailingPE on ETF proxies (SPY, QQQ, EXSA.DE, CAC.PA,
EXS1.DE, ISF.L, 1321.T, EEM), 2026-07-21.
Premium/discount to historical average midpoint: - S&P 500: +58% above historical average — historically stretched - Nasdaq 100: +14% above - Euro STOXX 600: +16% above - CAC 40: +17% above - DAX: +14% above - FTSE 100: +26% above — elevated - Nikkei 225: +2% above — roughly in line - MSCI EM: +20% above — elevated, at the boundary of the flag threshold
Investment Risk Assessment for ETF Investors
United States (S&P 500 / Nasdaq ETFs) SPY's live trailing P/E of 26.92x is 58% above the ~16-18x historical average — the most stretched valuation among major developed markets tracked here. Earnings yield = (1÷26.92) = 3.71%. Against the 10Y Treasury yield of 4.55% (FRED DGS10), the Equity Risk Premium is −0.84% — negative, meaning long bonds currently yield more than the S&P 500's earnings yield. Historically a negative or sub-1% ERP has been a caution signal for forward equity returns. The index is trading above both its 50-day (7,466.44) and 200-day (6,991.00) moving averages, within its 52-week range (6,212.69–7,620.90) — technically strong, but concentration in a handful of mega-cap names remains a structural risk. The 10Y TIPS real yield of 2.31% (FRED DFII10) is a meaningful headwind to further multiple expansion.
Europe (STOXX 600 / CAC 40 / DAX ETFs) EXSA.DE trailing P/E of 18.59x is 16% above the ~15-17x historical average — elevated but far less stretched than the U.S. Earnings yield = (1÷18.59) = 5.38%. Against the ECB AAA euro-area 10Y yield (Bund proxy) of 3.17% (ECB YC API, 2026-07-20), the EUR Equity Risk Premium is +2.21% — comfortably positive and a meaningfully better risk-reward setup than U.S. equities on this metric. European equities also trade at a persistent discount to the S&P 500 on trailing P/E (roughly 31% cheaper). Currency risk for non-EUR investors and ongoing fiscal/political overhang (e.g. France) remain the key risks.
Japan (Nikkei / TOPIX ETFs) 1321.T trailing P/E of 21.47x is only ~2% above the ~20-22x historical range — fair value by this metric, though today's post-holiday +3.26% surge in the Nikkei adds near-term momentum risk. The BOJ hiked its policy rate 25bps to 1.00% effective 2026-06-17 — the highest since 1995 — and board member commentary points toward a further move to a "neutral" ~2% over time. JPY currency-hedge decisions and BOJ policy risk remain the dominant considerations for non-JPY investors.
Emerging Markets (MSCI EM ETFs) EEM's trailing P/E of 16.86x is now 20% above its ~13-15x historical average — a rapid re-rating driven largely by today's chip-led Korea/Taiwan rally. EM still trades at a meaningful discount to the S&P 500 (37% cheaper on trailing P/E) but the valuation cushion has narrowed. Currency and political risk, and heavy index weighting to Northeast Asian tech names, remain the primary considerations.
Overall Risk Score (qualitative, not financial advice): - United States: High valuation risk — stretched P/E, negative ERP, real-yield headwind - Europe: Moderate — attractive relative valuation — positive ERP, discount to U.S. - Japan: Moderate — fair-value P/E, but BOJ policy and momentum risk - Emerging Markets: Moderate — valuation discount to DM has compressed after today's rally
Disclaimer: This is financial information, not personalised investment advice. Past valuations do not guarantee future returns. Consult a financial advisor before investing.
US Economic Indicators (FRED - authoritative)
| Indicator | Current | Prior | Delta | Reference Date | FRED Series |
|---|---|---|---|---|---|
| CPI YoY % | 3.46% | 4.17% | -0.71pp | June 2026 | CPIAUCSL |
| Core CPI YoY % | 2.57% | 2.82% | -0.25pp | June 2026 | CPILFESL |
| Unemployment Rate | 4.2% | 4.3% | -0.1pp | June 2026 | UNRATE |
| Nonfarm Payrolls | +57k m/m | — | — | June 2026 | PAYEMS |
| 10Y TIPS Real Yield | 2.31% | — | — | 2026-07-17 | DFII10 |
Both headline and core CPI YoY decelerated meaningfully in the June print, and unemployment edged down to 4.2% — a combination that, together with the resilient labor market (payrolls +57k), gives the FOMC room to hold steady at today's meeting, though markets will parse the statement closely for any tone shift.
Other economic releases today (from web search — timing/details not independently confirmed, treat with caution): - FOMC policy decision — scheduled 2:00pm ET; current target range 3.50–3.75% unchanged through this morning. This is the day's key event; no result yet. - ADP National Employment Report, S&P Global US Manufacturing PMI, and ISM Manufacturing Composite were flagged in economic-calendar sources as scheduled today, but this cluster of releases is atypical for a mid-month date — treat as unconfirmed pending official calendar verification.
Fixed Income & Bond Analysis
Policy Rates
| Central Bank | Rate | Source |
|---|---|---|
| Fed Funds (upper) | 3.75% | FRED DFEDTARU |
| Fed Funds (lower) | 3.50% | FRED DFEDTARL |
| Effective FFR | 3.63% | FRED DFF |
| ECB Deposit Rate | 2.25% | FRED ECBDFR |
| BOJ Policy Rate | 1.00% | web search — hiked 25bps 2026-06-17, highest since 1995 |
| BOE Bank Rate | ~3.73% (SONIA/FRED) | FRED IUDSOIA |
Government Bond Yields
| Country | 2Y Yield | 10Y Yield | 30Y Yield | Source |
|---|---|---|---|---|
| USA | 4.18% | 4.55% | 5.06% | FRED (2026-07-17) |
| Germany (AAA proxy) | 2.71% | 3.17% | 3.63% | ECB YC API (2026-07-20) |
| France | (not retrieved) | (not retrieved) | — | — |
| Italy | — | (not retrieved) | — | — |
| UK | 4.39% | 5.04% | — | web search |
| Japan | — | 2.73% | — | web search |
France and Italy 10Y yields, and the OAT-Bund spread, are not available today; the euro area AAA curve above is the source for the region.
Yield Curve Spreads (FRED pre-computed): - 10Y-2Y spread: +39 bps (FRED T10Y2Y, 2026-07-20) — positively sloped, but well short of a "steep" curve (>75bps); a normalizing, non-inverted curve. - 10Y-3M spread: +74 bps (FRED T10Y3M, 2026-07-20) — also positive, no recession signal from this indicator currently.
Both spreads indicate the curve has moved firmly out of inversion territory over the past two years and now sits in a modestly positive, "normal" shape — consistent with markets pricing continued but slowing disinflation rather than imminent recession.
Yield Curve Charts
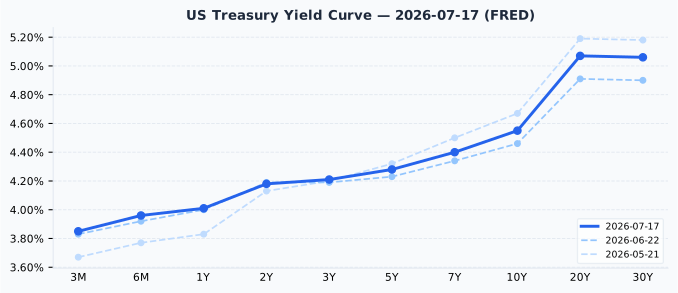
The US curve is upward-sloping across its full length with no inversion at any point, and short-end yields (3M: 3.85%, 6M: 3.96%) sit close to the Fed Funds midpoint (3.625%), as expected ahead of a hold decision. Versus one month ago (2026-06-22), yields at the belly and long end have risen 5-16bps (10Y: 4.46% → 4.55%; 20Y: 4.91% → 5.07%), a modest bear-steepening consistent with reduced near-term rate-cut expectations.
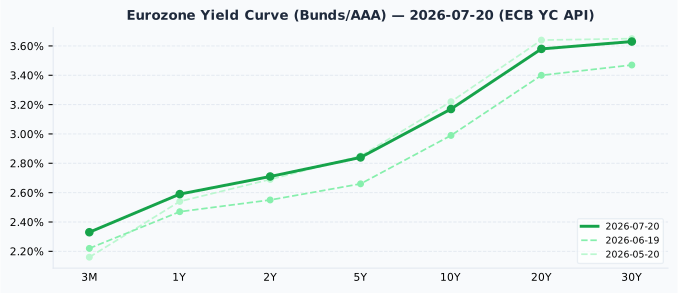
The Eurozone AAA curve is also upward-sloping throughout, with a wider long-end premium than the US curve in relative terms (30Y at 3.63% vs 3M at 2.33%, a spread of 130bps). Versus one month ago (2026-06-19), the curve has shifted up broadly by 12-18bps across most maturities, mirroring the US bear-steepening move.
Credit Markets (from FRED — authoritative)
| Market | OAS Spread | Series ID |
|---|---|---|
| US Investment Grade | 78 bps | BAMLC0A0CM |
| US High Yield | 269 bps | BAMLH0A0HYM2 |
| Euro High Yield | 252 bps | BAMLHE00EHYIOAS |
All three spreads sit at the tight end of, or below, their typical historical ranges (US IG normal 80-150bps; US HY normal 300-500bps) — both US HY and Euro HY are historically tight (sub-300bps), signaling continued risk-on complacency in credit markets rather than any stress, consistent with the risk-on equity tone described above, despite the VIX's moderate (not complacently low) 18.65 reading.
Bond Portfolio Implications
The Equity Risk Premium picture diverges sharply by region: - S&P 500 ERP = (1÷26.92) − 4.55% = −0.84% — negative. Bonds are currently yielding more than the earnings yield on U.S. equities, a historically unusual and cautionary setup that echoes Jamie Dimon's public caution today. - Euro ERP = (1÷18.59) − 3.17% = +2.21% — comfortably positive, a materially better relative value proposition for European equities versus European bonds than the U.S. equivalent.
Duration risk: with the 10Y at 4.55% and 30Y at 5.06%, a 100bps rise in yields would still produce roughly an 8-9% price loss on a 10Y bond — a meaningful risk for long-duration bond holders, though today's tight credit spreads suggest the market is not currently pricing material near-term stress. Given the negative U.S. ERP, some investors may see short-to-intermediate duration Treasuries (yielding 3.85-4.28% across 3M-5Y) as offering a more attractive risk-adjusted return than U.S. large-cap equities at current valuations — though this is not a recommendation, only a relative-value observation pending today's FOMC decision.
Currencies & Commodities
Currencies:
| Pair | Rate | Source |
|---|---|---|
| EUR/USD | 1.1440 | FRED DEXUSEU (2026-07-17) |
| USD Index | 120.53 | FRED DTWEXBGS (2026-07-17) |
| USD/JPY | 162.39 | web search (2026-07-17) |
| GBP/USD | 1.3454 | web search (2026-07-17) |
| USD/CHF | 0.808 | web search (2026-07-17/18) |
Commodities (all from yfinance front-month futures):
| Commodity | Price | Day Chg % | Ticker | Source |
|---|---|---|---|---|
| Brent Crude | $91.06 | +2.06% | BZ=F | yfinance |
| WTI Crude | $84.21 | +2.10% | CL=F | yfinance |
| Gold ($/oz) | $4,074.00 | +1.45% | GC=F | yfinance |
| Silver ($/oz) | $59.04 | +3.45% | SI=F | yfinance |
| Copper ($/lb) | $6.533 | +3.03% | HG=F | yfinance |
| Nat Gas ($/MMBtu) | $2.86 | 0.00% | NG=F | yfinance |
Gold and silver both remain well off their respective 52-week/all-time highs despite today's gains: gold at $4,074.00 is 27% below its all-time high of $5,586.20, and silver at $59.04 is 51% below its all-time high of $121.30 — both highs set within the past year, underscoring the scale of the recent pullback in precious metals. Copper, by contrast, is trading at $6.533/lb, just 1.8% below its all-time high of $6.6525 — effectively at/near record levels, reflecting continued strength in industrial/electrification demand. WTI ($84.21) and Brent ($91.06) remain 43% and 38% below their respective all-time highs of $147.27 and $147.43, well within normal historical trading ranges rather than any stress signal.
Sector & Theme Highlights
The dominant theme over the past month has been sector rotation rather than broad-based weakness: energy (+6.4%) and financials (+4.5%) have led, healthcare has rallied strongly (+7.4%), while semiconductors have lagged (-5.4%) — even as today's session saw chip names (Samsung, TSMC) drive the Asia-Pacific rally, suggesting the rotation narrative may be due for a near-term pause. Pharma/healthcare strength is echoed globally today by Novartis's Q2 beat ($5.94B core operating profit vs. $5.31B consensus). The gold/silver-versus-copper divergence described above is also a notable cross-asset theme: precious metals well off highs even as industrial metals push toward records, consistent with a market pricing stronger growth expectations over pure safe-haven demand right now.
Top Stories (Global)
- FOMC decision due 2:00pm ET today — Fed Funds target range currently 3.50-3.75%, unchanged; the day's key catalyst for global markets.
- US equities opened firmer Tuesday (S&P 500 +0.87%, Nasdaq 100 +1.93%, Dow +0.85%) ahead of the Fed decision.
- Novartis Q2 core operating profit of $5.94B beat consensus of $5.31B, supporting European healthcare sector strength.
- JPMorgan CEO Jamie Dimon publicly cautioned on both stocks and long-dated Treasurys, citing geopolitical tension (Ukraine, Middle East), rising fiscal deficits, and the risk of higher rates.
- USTR Jamieson Greer signaled new tariffs against multiple countries could be announced soon — a trade-policy risk to monitor for global equities and FX.
- Asia-Pacific rallied broadly (MSCI Asia Pacific +1.7%), led by Korea and Taiwan chipmakers (Samsung, TSMC) and Japan's post-holiday reopening (Nikkei +3.26%).
- Gold and silver both trade well below their respective all-time highs even as copper approaches record territory — a notable divergence within the commodity complex.
Looking Ahead
Key events, next 1-5 trading days: - FOMC policy decision — today, 2026-07-21, 2:00pm ET. The dominant near-term catalyst; no result yet at the time this briefing covers. - Ongoing Q2 earnings season (Novartis reported today; broader European and U.S. earnings flow continues into next week). - Markets will watch for confirmation/detail on the ADP, PMI, and ISM Manufacturing releases flagged as scheduled today — treat with caution pending calendar verification.
Market closures (next 5 calendar dates, from holiday calendar): - 2026-08-01 — Switzerland: Swiss National Day (Bundesfeier) — Swiss markets closed. - 2026-08-11 — Japan: Mountain Day (山の日) — Japanese markets closed. - 2026-08-15 — France: Assumption Day (Assomption) — French markets closed. - 2026-08-17 — South Korea: Liberation Day (광복절) — Korean markets closed. - 2026-08-31 — United Kingdom: Summer Bank Holiday — UK markets closed.
No market closures are scheduled among tracked countries (US, GB, DE, FR, JP, AU, CH, CA, KR, BR, IN) before 2026-08-01.