2026 10 02
Global Financial Briefing — Friday, 2 October 2026
Figures reflect the 2 October close wherever a close exists, and US Treasury figures and the US yield curve chart use Treasury's settled 2 October par curve. FX quotes and the German, French, UK, Japanese and Italian bond yields are afternoon quotes; the euro AAA curve is the 1 October curve, the latest the ECB has published; other figures are dated inline.
Market Overview
A weak US jobs report and stronger euro-area inflation pulled in opposite directions today, and shares came out ahead. US employers added only 29,000 jobs in September against about 84,000 expected, the unemployment rate rose to 4.2% from 4.1%, and the July and August figures were revised down by a combined 60,000, leaving July at a loss of 10,000 jobs (BLS, CNBC). After the release, traders cut the chance of a Fed rate rise at the 27–28 October meeting to about 17%, from 64% a week earlier (CME FedWatch, via CNBC and Yahoo Finance). Treasury yields fell straight after the release and then turned higher: the 10-year settled at 5.28%, up 4 bp on the day, and the 2-year and 5-year at 4.83% and 5.06%, both up 5 bp (US Treasury par curve, 2 Oct). CNBC quoted one market observer saying the report did not change the Fed's path of keeping rates high for longer, and traders still expect a rise in December.
In Europe, September's flash inflation came in at 3.8%, above the 3.6% forecast and up from 3.2% in August, the highest since September 2023, while core inflation, which leaves out energy, food, alcohol and tobacco, rose as expected to 2.5% from 2.4% (FXStreet). Bond markets split by maturity: the German 2-year yield, the one most tied to expected ECB rates, rose 2 bp to 3.07%, while the 10-year fell 6 bp to 3.46%, after touching a 17-year high, and the 30-year 9 bp to 3.82% (Trading Economics). Italian and French 10-year yields fell 10 bp and 4 bp. US crude fell after the G7 agreed to release up to 100 million barrels of crude and diesel from emergency reserves over four months, coordinated by the International Energy Agency, with a large diesel release in the first 20 days (NBC News, BNN Bloomberg). The November WTI contract (CLX26) settled 1.90% lower at $91.11, while December Brent (BZZ26) settled almost unchanged at $102.25, down 0.06% (EnergyNow).
Shares rose on both sides of the Atlantic. The STOXX 600 gained 0.75% and the DAX 1.17%, recovering from a three-and-a-half-month low, though the STOXX 600 still lost 1.9% over the week (Trading Economics). In New York the S&P 500 closed up 0.73%, the Dow 0.49% and the Nasdaq 100 1.00% at 30,807.93, a record close above the previous one of 30,762. Nvidia touched an intraday record of $237.88 and closed 1.34% higher at $233.95, and Tesla rose 4.65% after third-quarter deliveries of 486,532 beat the 463,000 expected (Yahoo Finance). Brazil's Ibovespa jumped 2.63% to 192,115, its largest gain since 2 September and highest close since 22 April, on the last session before Sunday's first-round general election, led by Bradesco (+3.8%), Petrobras (+2.5%) and Vale (+2.4%), according to The Rio Times, while the real weakened about 0.8% against the dollar (Yahoo Finance). Asia closed before the US jobs data and saw none of it: Hong Kong reopened after its National Day holiday and the Hang Seng fell 2.60%, its largest one-day fall since March, led by AIA (−6.0%) and HSBC (down nearly 5%), and the Nikkei gave back 0.94% of Thursday's 3.30% rise. Mainland China was closed for National Day (investinglive), and Yahoo Finance shows no Indian session today.
Global Indices Snapshot
Americas
| Index | Level | Day Chg | Day Chg % | Source |
|---|---|---|---|---|
| S&P 500 | 7,722.72 | +56.27 | +0.73% | yfinance ^GSPC |
| Nasdaq 100 | 30,807.93 | +306.37 | +1.00% | yfinance ^NDX |
| Dow Jones | 51,176.96 | +250.40 | +0.49% | yfinance ^DJI |
| Brazil IBOV | 192,114.55 | +4,917.09 | +2.63% | yfinance ^BVSP |
Americas data reflects the 2 Oct close.
Europe
| Index | Level | Day Chg | Day Chg % | Source |
|---|---|---|---|---|
| Euro STOXX 600 | 631.35 | +4.70 | +0.75% | yfinance ^STOXX |
| CAC 40 | 7,897.19 | +61.88 | +0.79% | yfinance ^FCHI |
| DAX | 25,231.20 | +291.85 | +1.17% | yfinance ^GDAXI |
| FTSE 100 | 10,461.95 | +33.68 | +0.32% | yfinance ^FTSE |
| SMI (Swiss) | 13,660.92 | +38.07 | +0.28% | yfinance ^SSMI |
European data reflects the 2 Oct 2026 close.
Asia-Pacific
| Index | Level | Day Chg | Day Chg % | Source |
|---|---|---|---|---|
| Nikkei 225 | 68,309.46 | −647.26 | −0.94% | yfinance ^N225 |
| Hang Seng | 23,972.29 | −640.98 | −2.60% | yfinance ^HSI |
| Shanghai Comp | 3,842.19 ‡ | — | — | yfinance 000001.SS |
| ASX 200 | 8,682.10 | +67.70 | +0.79% | yfinance ^AXJO |
| Kospi (Korea) | 7,003.74 | +32.39 | +0.46% | yfinance ^KS11 |
Asia-Pacific data reflects the 2 Oct 2026 close.
‡ Shanghai Comp: data reflects the 30 Sep 2026 close.
The Hang Seng's change is measured from its 30 September close, because Hong Kong was shut for National Day on 1 October, so it covers two days of global moves. Insurer AIA fell 6.0%, Xiaomi 4.0%, the exchange operator HKEX 3.1% and Tencent 2.3% (Trading Economics), and HSBC nearly 5% (Futu News); the index touched its lowest in nearly three months. With mainland markets closed until 8 October, the Stock Connect link that lets mainland investors buy Hong Kong shares was also shut. Shanghai's level is its 30 September close.
Emerging Markets
| Index | Level | Day Chg % | Source |
|---|---|---|---|
| MSCI EM (EEM) | 67.67 | +1.29% | yfinance EEM |
| India Nifty 50 | 22,421.95 ‡ | — | yfinance ^NSEI |
| South Africa | 63.19 | +0.52% | yfinance EZA |
Emerging-market data reflects the 2 Oct close.
‡ India Nifty 50: data reflects the 1 Oct 2026 close.
EEM rose 1.29% in New York while the Asian markets that make up most of the MSCI EM index had closed before the US jobs report: the Hang Seng fell 2.60% and the Kospi rose 0.46%, mainland China was closed and India's index shows no session today. EEM's gain is New York's valuation of emerging markets after the report, not what those markets did today; Asia's sessions on Monday will show whether it holds. India's Nifty level is its 1 October close; Yahoo Finance recorded no session today.
Index Valuations & Investment Risk
Valuation Table
| Index | Trailing P/E (live) | 50-day avg | 100-day avg | 200-day avg |
|---|---|---|---|---|
| S&P 500 | 24.9x | 25.6x | 26.4x | — |
| Nasdaq 100 | 30.6x | 30.2x | 31.8x | — |
| Euro STOXX 600 | 17.4x | 18.1x | 18.2x | — |
| CAC 40 | 16.1x | 17.2x | 17.3x | — |
| DAX | 17.9x | 18.6x | 18.5x | — |
| FTSE 100 | 14.9x | 17.2x | 17.5x | — |
| Nikkei 225 | 22.7x | 21.8x | 22.7x | — |
| MSCI EM | 14.4x | 15.9x | 16.8x | — |
Averages of the daily trailing P/E readings recorded since 1 May 2026 (n = 102); shown for reference only. Trailing P/E is Yahoo Finance's trailing P/E for the ETF proxies SPY, QQQ, EXSA.DE, CAC.PA, EXS1.DE, ISF.L, 1321.T and EEM at the 2 Oct close.
Investment Risk Assessment for ETF Investors
United States (S&P 500 / Nasdaq ETFs)
The S&P 500's trailing P/E of 24.9x gives an earnings yield of 4.02% (1÷24.87). Against the 10-year Treasury at 5.28% (US Treasury par curve, 2 Oct) the earnings yield gap is −1.26 pp: a 10-year government bond pays more in income today than the index's earnings amount to per dollar invested. Against the real 10-year yield of 2.92% (US Treasury real curve, 2 Oct) the gap is +1.10 pp; the 2.36 pp between the two is the correction for company earnings growing with inflation while a bond coupon is fixed. Only the part of earnings paid out as dividends and buybacks reaches a holder as cash. The index closed 1.20% below its 52-week high of 7,816.70 and 6.94% above its 200-day average (7,221), so its price has adjusted little to a 10-year yield above 5%. The Nasdaq 100 at 30.6x has an earnings yield of 3.27%, 2.01 pp below the 10-year Treasury, and closed at a record. Today's jobs report lowers the odds of a Fed rise this month, which helps the shares whose value rests on profits far in the future, but a 10-year yield that closed 4 bp higher despite the weak report shows how little relief the bond market is giving them.
Europe (STOXX 600 / CAC 40 / DAX ETFs)
The STOXX 600 at 17.4x gives an earnings yield of 5.75% (1÷17.40); against the 10-year Bund at 3.46% (Trading Economics, 2 Oct, afternoon) the euro earnings yield gap is +2.29 pp, and against the 1 October AAA euro curve's 3.59% it is +2.16 pp. Against the euro-area real 10-year yield of 1.56% (see Real Yields below) it is +4.19 pp. The S&P 500 trades at a 42.9% P/E premium to the STOXX 600 (24.9x against 17.4x). Part of the difference between the US and euro gaps reflects different inflation and policy paths rather than different compensation for risk, which is why the real-yield versions are shown alongside. The CAC 40 at 16.1x has an earnings yield of 6.21%, while the French 10-year bond pays 4.87%, so a French saver gives up 1.34 pp of current yield by holding French bonds rather than French shares, against 2.29 pp for the STOXX 600 measured on the Bund. The CAC 40 rose 0.79% today but remains 5.46% below its 50-day and 4.15% below its 200-day average, the weakest of the European indices on both measures. September's 3.8% inflation raises the chance of a further ECB rate rise after the 10 September move to 2.50%. A euro investor in euro-quoted funds has no exchange-rate effect on the quoted value, but the constituents earn much of their profit abroad, so moves in the euro still change the euro value of those earnings.
Japan (Nikkei / TOPIX ETFs)
The Nikkei ETF proxy trades at 22.7x after the index fell 0.94% today, giving back part of Thursday's 3.30% chip-led rise. The Bank of Japan raised its policy rate to 1.25% on 18 September, its second rise this year after the 16 June move to 1.00%, and on 2 October markets priced about an 83% chance of no change at its 28 October meeting (rateprobability.com). The 10-year JGB yield was 3.11%, up 1 bp, easing from a 30-year high (Trading Economics). The yen firmed 0.18% to 157.76 per dollar. For a euro investor an unhedged Japan fund carries the yen's moves in full, so the choice between hedged and unhedged matters as much as the view on Japanese shares.
Emerging Markets (MSCI EM ETFs)
EEM trades at 14.4x, the cheapest of the eight indices in the table and a 42.1% discount to the S&P 500. Its 1.29% rise today is New York's pricing after the US jobs report, while Hong Kong, which closed before it, fell 2.60% (see Emerging Markets above). A lower chance of a Fed rise this month helps emerging markets through their economies: companies and governments with dollar debt face lower servicing costs if US rates stop rising, and foreign money is less inclined to leave. Those effects reach local share prices whatever currency the investor spends. For a euro holder the currency conversion itself matters less, because the euro and emerging-market currencies tend to move the same way against the dollar.
Overall Risk Score: - United States: High valuation risk / low margin of safety. A negative nominal earnings yield gap, an index about 1% from its 52-week high, and a 10-year yield above 5%. - Europe: Moderate. Positive earnings yield gaps on both measures, but euro-area inflation at 3.8% and French borrowing costs near their highest since 2002 and Italian ones near their highest since 2023. - Japan: Moderate. A P/E of 22.7x, close to the US level; BOJ rate rises and the yen are the main risks. - Emerging Markets: Attractive relative valuation, with high US yields and Hong Kong's 2.60% fall as the near-term headwinds.
US Economic Indicators (FRED - authoritative)
| Indicator | Current | Prior | Delta | Reference Date | FRED Series |
|---|---|---|---|---|---|
| CPI YoY % | 3.35% | 3.30% | +0.05 pp | Aug 2026 (prior Jul) | CPIAUCSL |
| Core CPI YoY % | 2.45% | 2.47% | −0.02 pp | Aug 2026 (prior Jul) | CPILFESL |
| Unemployment Rate | 4.2% | 4.1% | +0.10 pp | Sep 2026 (prior Aug) | UNRATE |
| Nonfarm Payrolls | +29k | +133k | −104k | Sep 2026 (prior Aug), monthly chg | PAYEMS |
| 10Y TIPS Real Yield | 2.92% | 2.88% | +4 bp | 2 Oct 2026 (prior 1 Oct) | DFII10 (US Treasury real curve) |
The table's September labour figures are today's release. The 4.2% unemployment rate rose partly because more people joined the labour force, with participation at 61.8% (BLS, CNBC). Health care added 17,000 jobs, construction 11,000 and manufacturing 9,000, while financial activities lost 7,000. Average hourly earnings rose 0.1% on the month to $37.81 and 3.0% on the year (BLS), below August CPI inflation of 3.35%, so wages are not keeping up with prices. The CPI figures are August's; September's are due on 14 October (BLS).
Other economic releases today (web search)
| Release | Actual | Consensus | Prior | Note |
|---|---|---|---|---|
| US nonfarm payrolls (Sep) | 29k | 84k | 133k | well below; July revised to −10k from +21k, August to +133k from +162k, combined 60k lower; health care +17k, construction +11k, manufacturing +9k, financial activities −7k (BLS, CNBC) |
| US unemployment rate (Sep) | 4.2% | 4.1% | 4.1% | above; participation 61.8%; rise partly from people joining the labour force (BLS, CNBC) |
| US average hourly earnings (Sep) | +0.1% m/m, +3.0% y/y | — | — | up 5 cents to $37.81 (BLS) |
| Euro area flash HICP (Sep) | 3.8% | 3.6% | 3.2% | above; highest since September 2023; +0.6% m/m (FXStreet) |
| Euro area flash core HICP (Sep) | 2.5% | 2.5% | 2.4% | in line (FXStreet) |
Fixed Income & Bond Analysis
Policy Rates
| Central Bank | Rate | Source |
|---|---|---|
| Fed Funds (upper) | 4.00% | FRED DFEDTARU (2 Oct 2026) |
| Fed Funds (lower) | 3.75% | FRED DFEDTARL (2 Oct 2026) |
| Effective FFR | 3.88% | FRED DFF (1 Oct 2026) |
| ECB Deposit Rate | 2.50% | FRED ECBDFR (2 Oct 2026) |
| BOJ Policy Rate | 1.25% | web search (raised 18 Sep 2026, effective 24 Sep; next meeting 28 Oct) |
| BOE Bank Rate | 3.73% | FRED IUDSOIA (30 Sep 2026) |
Government Bond Yields
| Country | 2Y Yield | 10Y Yield | 30Y Yield | Day Chg (10Y) | Source |
|---|---|---|---|---|---|
| USA | 4.83% | 5.28% | 5.63% | +4 bp | US Treasury par curve (2 Oct 2026) |
| Germany | 3.07% | 3.46% | 3.82% | −6 bp | web (Trading Economics, 2 Oct 2026 intraday) |
| France | — | 4.87% | — | −4 bp | web (Trading Economics, 2 Oct 2026 intraday) |
| UK | 4.68% | 5.37% | 5.89% | −2 bp | web (Trading Economics, 2 Oct 2026 intraday) |
| Japan | 1.93% | 3.11% | 4.21% | +1 bp | web (Trading Economics, 2 Oct 2026 intraday) |
| Italy | — | 4.61% | — | −10 bp | web (Trading Economics, 2 Oct 2026 intraday) |
The USA day change is against the 1 Oct 2026 curve from the same feed.
Yield Curve Spreads (US Treasury par curve, 2 Oct 2026): - 10Y-2Y spread: +45 bp, positive, 20 bp outside the ±25 bp flat band and under the 75 bp steep threshold, −1 bp on the day. - 10Y-3M spread: +109 bp, positive, no recession signal, +2 bp on the day.
OAT-Bund Spread: 141 bp (10-year OAT 4.87% against Bund 3.46%, Trading Economics, 2 Oct 2026 intraday).
US yields rose at every maturity except six months, which was unchanged, after the jobs report despite its weakness: the 2-year by 5 bp to 4.83%, the 10-year by 4 bp to 5.28% and the 30-year by 2 bp to 5.63%, so the curve flattened slightly. In Europe today's quotes show a curve that flattened: the German 2-year rose 2 bp while the 30-year fell 9 bp, so the gap between short and long German yields narrowed by about 11 bp on a day when inflation surprised on the upside. The OAT-Bund spread, 141 bp, is the extra yield investors demand to hold French rather than German 10-year debt; it widened 2 bp, as the Bund yield fell more than the OAT's (6 bp against 4 bp). Italy's yield fell most, by 10 bp. The UK 10-year gilt eased 2 bp to 5.37% after touching its highest since July 2007, and the 30-year 5 bp to 5.89%, back below 6% (Trading Economics).
Yield Curve Charts
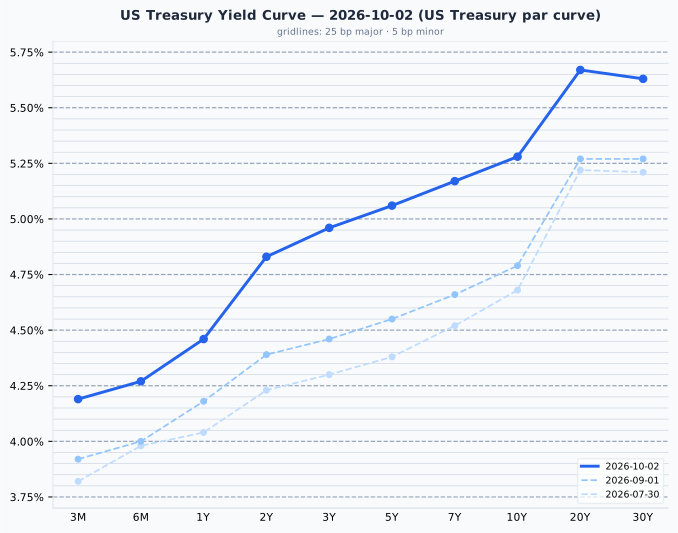
US Treasury par curve, 2 Oct 2026: 3M 4.19%, 6M 4.27%, 1Y 4.46%, 2Y 4.83%, 3Y 4.96%, 5Y 5.06%, 7Y 5.17%, 10Y 5.28%, 20Y 5.67%, 30Y 5.63%; 2-to-10 slope +45 bp. Day change against the 1 Oct 2026 curve: 3M +2 bp, 6M 0 bp, 1Y +2 bp, 2Y +5 bp, 3Y +5 bp, 5Y +5 bp, 7Y +5 bp, 10Y +4 bp, 20Y +3 bp, 30Y +2 bp. The 3-month bill at 4.19% is about 31 bp above the Fed funds midpoint of 3.875%.
The US curve rises from 4.19% at three months to 5.67% at 20 years, with the 30-year 4 bp below the 20-year. Since 1 September every maturity is higher, most in the middle of the curve (+51 bp at five and seven years, +49 bp at ten) and least at three and six months (+27 bp), with the 2-year up 44 bp and the 30-year 36 bp.
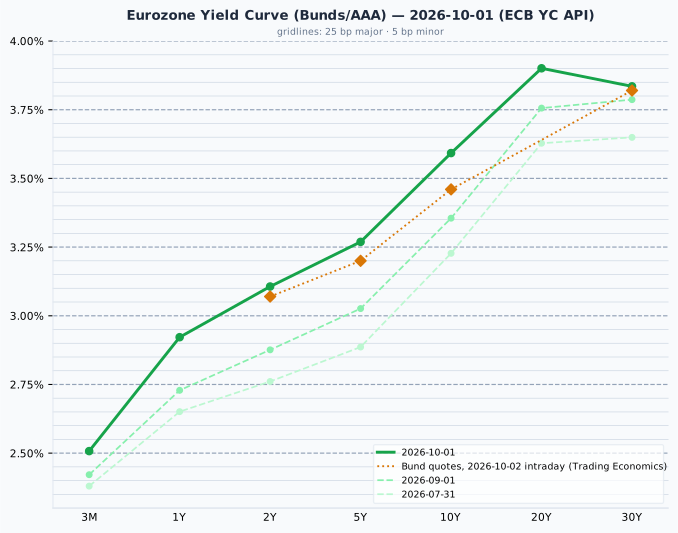
Euro area AAA government curve, 1 Oct 2026 (ECB YC API): 3M 2.51%, 1Y 2.92%, 2Y 3.11%, 5Y 3.27%, 10Y 3.59%, 20Y 3.90%, 30Y 3.84%; 2-to-10 slope +49 bp. Today's Bund quotes (Trading Economics, 2 Oct 2026), overlaid, differ from the plotted 1 Oct 2026 curve by at most 13 bp, at the 10Y (3.46% against 3.59%); the curve is the ECB's fitted AAA euro-area composite and the quotes are on-the-run Bunds, which sit a few basis points apart by construction, so only a gap well beyond that is a day move.
The euro AAA curve rises from 2.51% at three months to 3.90% at 20 years. Since 1 September it has risen by 9 bp at three months and 24 bp at the 10-year, the 2-year gaining 23 bp after the ECB's 10 September rate rise to 2.50%.
Credit Markets (from FRED - authoritative)
| Market | OAS | Obs. date | vs prior obs | Series ID |
|---|---|---|---|---|
| US Investment Grade | 86 bp | 1 Oct 2026 | +2 bp | BAMLC0A0CM |
| US High Yield | 324 bp | 1 Oct 2026 | +12 bp | BAMLH0A0HYM2 |
| Euro High Yield | 317 bp | 1 Oct 2026 | +17 bp | BAMLHE00EHYIOAS |
Change is 1 Oct 2026 vs 30 Sep 2026. Credit spreads are the 1 October close; today's session is not in them yet.
Spreads widened on 1 October, the day long-term government bond yields reached multi-decade highs and European shares fell: US high yield by 12 bp to 324 bp and euro high yield by 17 bp to 317 bp. Both remain inside the 300–500 bp range normal for high yield, and US investment grade at 86 bp is inside its 80–150 bp range.
Real Yields (US and Euro Area)
| Region | Nominal 10Y | Expected inflation | Real 10Y | How the real yield is obtained |
|---|---|---|---|---|
| United States | 5.28% (US Treasury par curve, 2 Oct 2026) | 2.36% (residual: nominal − real) | 2.92% (US Treasury real curve, 2 Oct 2026) | Measured. TIPS trade, so the market quotes a real yield directly; expected inflation is the residual (the breakeven) |
| Euro area | 3.59% (ECB YC API, 1 Oct) | 2.04% (ECB SPF, 2026 Q3, measured) | 1.56% (residual: nominal − expected) | Constructed. No euro inflation-linked benchmark is published, so a survey expectation is subtracted from the nominal yield |
Only the US real yield is a market price; the euro figure is derived from a survey and is the softer of the two. Two mismatches apply when comparing them: the US breakeven includes a premium investors demand for inflation risk, which a survey does not, and the survey looks five years ahead against the bond's ten. The US leg is dated 2 October and the euro leg 1 October, the latest curve the ECB has published. The 169 bp gap between US and euro nominal 10-year yields splits into 32 bp of expected-inflation difference (2.36% against 2.04%) and 136 bp of real-rate difference (2.92% against 1.56%), so the gap is almost entirely real. The US real yield rose 4 bp on 2 October to 2.92% (against 2.88% on 1 October).
Why the US real-yield advantage is not a return a euro investor can capture
The US real yield has exceeded the euro one in every quarter since 2014, by 1.52 pp on average, and today's 136 bp is under that mean. It is a structural feature (US trend growth, euro-area savings, Bund scarcity, US fiscal supply), not a trade a EUR-based reader can capture: hedging the currency removes it, because the forward rate is set from the same interest differential, and holding Treasuries unhedged is a dollar bet rather than a bond decision. A real yield is real in its own currency; a US real yield of 2.92% is that much above US inflation, which is not a real return for someone who spends euros. The gap is stated here as a description of relative policy stance and growth expectations, and no portfolio conclusion is drawn from it.
Bond Portfolio Implications
A 10 bp rise in yields is an ordinary day's move. At the 2 Oct 2026 par yields it costs:
| Maturity | Yield | Modified duration | Loss for a 10 bp rise | Months of coupon lost |
|---|---|---|---|---|
| 2-year | 4.83% | 1.88 | 0.19% | 0.5 |
| 10-year | 5.28% | 7.69 | 0.77% | 1.7 |
| 30-year | 5.63% | 14.40 | 1.42% | 3.0 |
Months of coupon lost is the loss divided by one month of coupon (yield ÷ 12) on a par bond. Source: US Treasury par curve, 2 October.
Today's 4 bp rise at the 10-year cost a holder about 0.3%, or 0.7 months of coupon. The swing within the session, from a fall after the jobs report to a rise by the close, is a reminder that long bonds can move against a holder on news that looks favourable. The US 2-year pays 4.83% with about a quarter of the 10-year's price sensitivity, so short maturities still offer most of the income for far less exposure while long yields swing this much.
Currencies & Commodities
Currencies (Yahoo Finance live quotes)
| Pair | Rate | Day chg % | Source |
|---|---|---|---|
| EUR/USD | 1.1261 | +0.15% | yfinance (18:10 CEST) |
| USD Index (DXY, ICE) | 101.91 | −0.19% | yfinance (18:00 CEST) |
| USD/JPY | 157.76 | −0.18% | yfinance (18:10 CEST) |
| GBP/USD | 1.3235 | +0.31% | yfinance (18:10 CEST) |
| USD/CHF | 0.8288 | −0.18% | yfinance (18:10 CEST) |
FX quotes as of 18:10 CEST; day change vs the previous 17:00 ET close.
The dollar eased after the jobs report: the ICE dollar index fell 0.19% and the euro rose 0.15% to $1.1261, still below $1.13, a level it broke on Thursday for the first time since May 2025. Sterling gained 0.31%.
Commodities (Yahoo Finance front-month futures)
| Commodity | Price | Day Chg % | Ticker | Source |
|---|---|---|---|---|
| Brent Crude ($/bbl) | 102.25 | −0.06% | BZ=F | yfinance (BZZ26, Dec) |
| WTI Crude ($/bbl) | 91.11 | −1.90% | CL=F | yfinance (CLX26, Nov) |
| Gold ($/oz) | 4,162.30 | −0.95% | GC=F | yfinance (GCZ26, Dec) |
| Silver ($/oz) | 60.415 | −1.24% | SI=F | yfinance (SIZ26, Dec) |
| Copper ($/lb) | 6.5490 | +0.17% | HG=F | yfinance (HGZ26, Dec) |
| Nat Gas ($/MMBtu) | 3.035 | +2.29% | NG=F | yfinance (NGX26, Nov) |
Day changes are settlement-to-settlement: 2 Oct settlement vs 1 Oct settlement.
The December Brent contract (BZZ26) settled almost unchanged at $102.25, down 0.06%, while November WTI (CLX26) fell 1.90% to $91.11, both in the upper half of their 52-week ranges ($58.72 to $126.10 for Brent, $54.98 to $119.48 for WTI), after the G7 agreed to release up to 100 million barrels of crude and diesel reserves over four months. The agreement follows a 400 million barrel release in March (NBC News). Trading Economics also cited Gulf exports recovering close to their pre-war levels, while reported tanker attacks keep shipping risk in the price. WTI fell more than Brent, so the gap between them (December Brent against November WTI) widened to $11.14 from $9.44 at Thursday's settlements.
Gold fell 0.95% to $4,162.30, 25.5% below its all-time high of $5,586.20 set on 29 January 2026, and silver 1.24% to $60.415, 50.2% below its all-time high of $121.30 set the same day. Copper rose 0.17% to $6.549, slightly below its all-time high of $6.83 set on 22 September. Natural gas rose 2.29% to $3.035, near the bottom of its 52-week range of $2.483 to $7.827.
Sector & Theme Highlights
US sector funds (Select Sector SPDRs, 2 Oct close): consumer discretionary (XLY) +1.13% led, followed by technology (XLK) +1.01%, industrials (XLI) +0.78%, materials (XLB) +0.66%, utilities (XLU) +0.38%, communication services (XLC) +0.35%, real estate (XLRE) +0.32%, consumer staples (XLP) +0.25% and energy (XLE) +0.19%. Financials (XLF) +0.06% and health care (XLV) −0.01% were flat.
- Chipmakers: Nvidia touched an intraday record of $237.88 and closed 1.34% higher (Yahoo Finance), and in Europe ASML gained 3.51% and technology shares rose 2.5%, the best sector in the STOXX 600 (Trading Economics).
- Emergency oil reserves: the G7's release of up to 100 million barrels, with a large diesel release in the first 20 days, lowered US crude by 1.90% while Brent held near $102; the US energy fund still edged up 0.19% after leading on Thursday.
- Hong Kong financials: AIA (−6.0%) and HSBC (nearly −5%) led the Hang Seng's 2.60% fall on its first session since 30 September.
- Euro-area inflation: the 3.8% flash reading lifted the German 2-year yield, the maturity most tied to expected ECB rates, while longer German yields fell with French, Italian and UK yields.
Top Stories (Global)
- US hiring nearly stalls. Payrolls rose 29,000 in September against about 84,000 expected, unemployment rose to 4.2%, and July and August were revised down by 60,000 combined; the chance of an October Fed rise fell to about 17% after the release, from 64% a week earlier (BLS, CNBC, Yahoo Finance).
- Treasury yields turn higher anyway. After an initial fall, the 10-year settled 4 bp higher at 5.28% (US Treasury par curve), with traders still expecting a December rise (CNBC).
- Euro-area inflation jumps to 3.8%. September's flash reading beat the 3.6% forecast and was the highest since September 2023; core inflation rose to 2.5% as expected (FXStreet).
- G7 releases emergency oil. Up to 100 million barrels of crude and diesel over four months, coordinated by the IEA; WTI settled 1.90% lower while Brent was almost unchanged (NBC News, BNN Bloomberg, EnergyNow).
- Hang Seng's largest fall since March. The index lost 2.60% to 23,972 as Hong Kong reopened after National Day, led by AIA, Xiaomi and HSBC (Trading Economics, Futu News).
- European shares rebound from a three-and-a-half-month low. The DAX rose 1.17% and the STOXX 600 0.75%, with ASML up 3.51%, but the STOXX 600 still fell 1.9% on the week (Trading Economics).
- Tesla deliveries beat. Third-quarter deliveries of 486,532 against 463,000 expected sent the shares up 4.65% (Yahoo Finance).
- Brazilian shares jump before the election. The Ibovespa rose 2.63% to 192,115, its highest close since 22 April, in the last session before Sunday's first-round vote (The Rio Times).
Looking Ahead
- Monday 5 October: US ISM services index and final services and composite PMIs for September (Newsquawk).
- Tuesday 6 October: German factory orders and euro-area retail sales for August (Newsquawk).
- Wednesday 7 October: minutes of the Fed's 16 September meeting, at which it raised its target range to 3.75–4.00%; they may show how many members wanted to move again soon (Newsquawk).
- Thursday 8 October: account of the ECB's September meeting, read for the appetite for a further rise after today's 3.8% inflation; mainland Chinese markets reopen after National Day.
- Friday 9 October: Canadian September jobs report and the University of Michigan's preliminary October consumer sentiment (Newsquawk). An OPEC+ meeting takes place on Sunday 4 October (Newsquawk).
- Later this month: the Fed meets on 27–28 October and the Bank of Japan on 28 October.
Market closures - Germany, Saturday 3 Oct 2026: Tag der Deutschen Einheit. - Korea, Monday 5 Oct 2026: National Foundation Day. - Further out: Korea 9 Oct 2026 (Hangul Day); Brazil 12 Oct 2026 (Nossa Senhora Aparecida); Canada 12 Oct 2026 (Thanksgiving); Japan 12 Oct 2026 (Sports Day); United States 12 Oct 2026 (Columbus Day: bond market closed, stock exchanges open). - No Indian holiday data is available here, so Indian closures are not checked.
Data sources: US Treasury par and real curves (2 Oct 2026) and FRED (policy rates, VIX, credit spreads, macro); ECB YC API (AAA curve, 1 Oct 2026) and ECB SPF (2026 Q3); equity indices, ETF P/E proxies, commodity futures and FX via Yahoo Finance (US-listed instruments and commodity settlements at the 2 Oct close, FX as of 18:10 CEST); European, UK and Japanese bond yields, economic releases and news via web search (Trading Economics, BLS, CNBC, Yahoo Finance, FXStreet, NBC News, BNN Bloomberg, EnergyNow, The Rio Times, Futu News, rateprobability.com, Quifinanza).